Salesforce Q2 FY27: EPS doubled, operations didn't
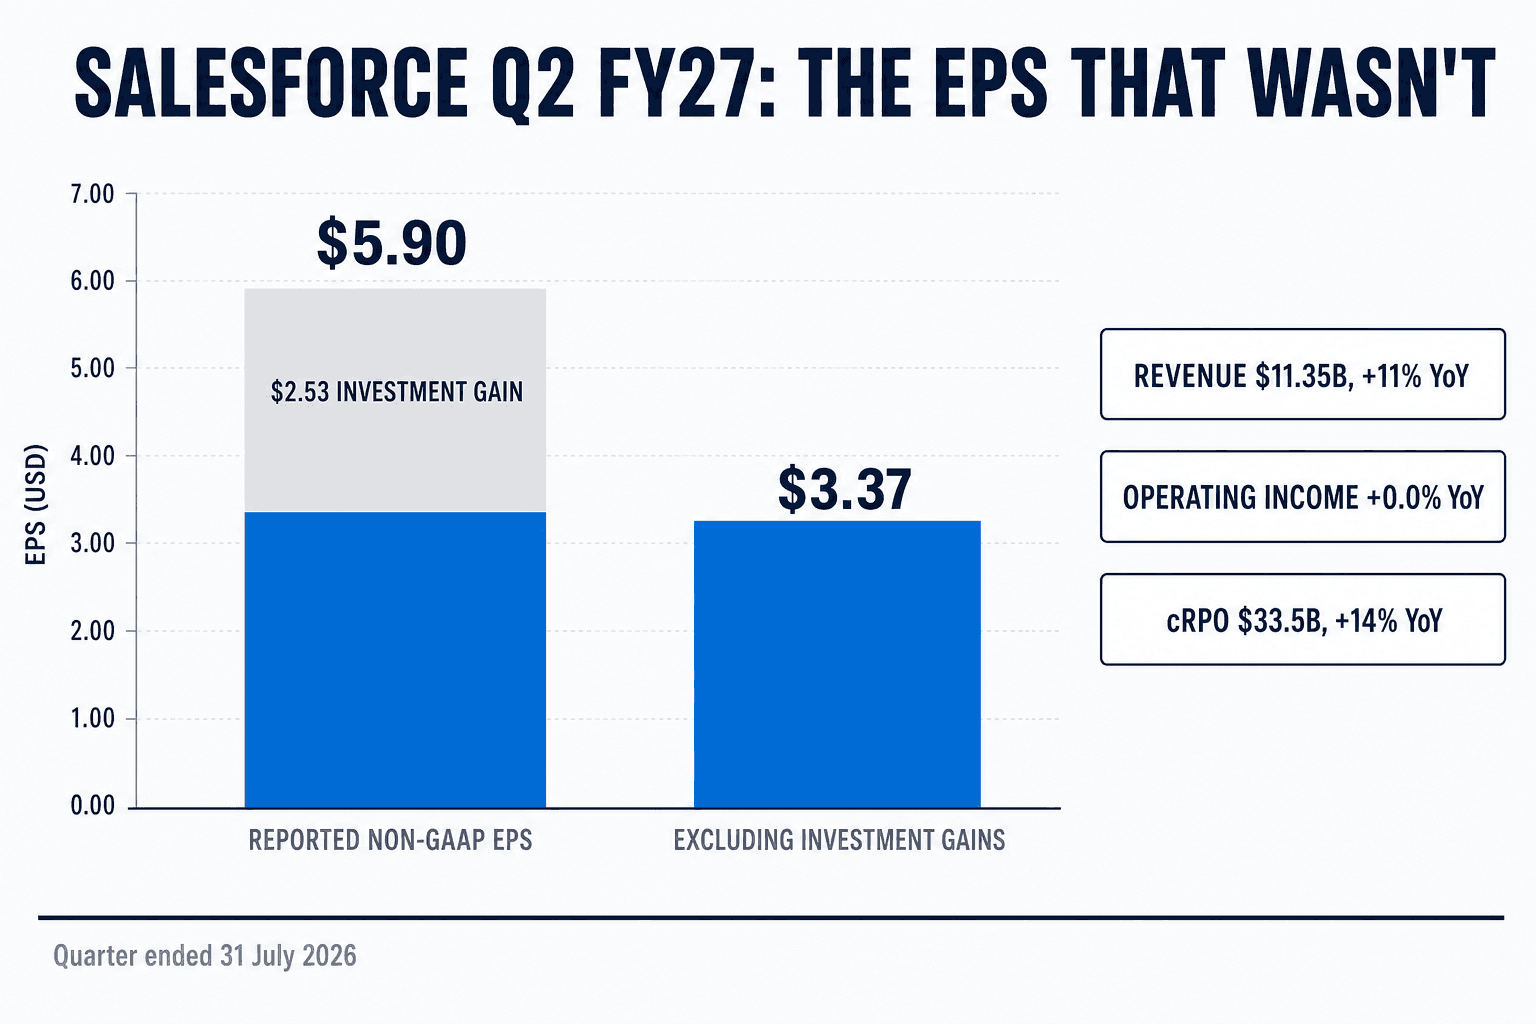
Salesforce reported non-GAAP earnings per share of $5.90 on Wednesday evening against its own guide of $3.25 to $3.27. The stock settled about 13% higher after hours, then did something unusual: it kept going, closing the next session up 22.58% at $252.05, its second-best day in company history.
Here is the part almost nobody priced. Salesforce discloses, in its own release, exactly how much of that EPS came from a mark-to-market gain on its investment portfolio. Take the company's number out, and non-GAAP EPS grew 15.8%, not 103%. On a GAAP basis it fell.
The EPS that wasn't
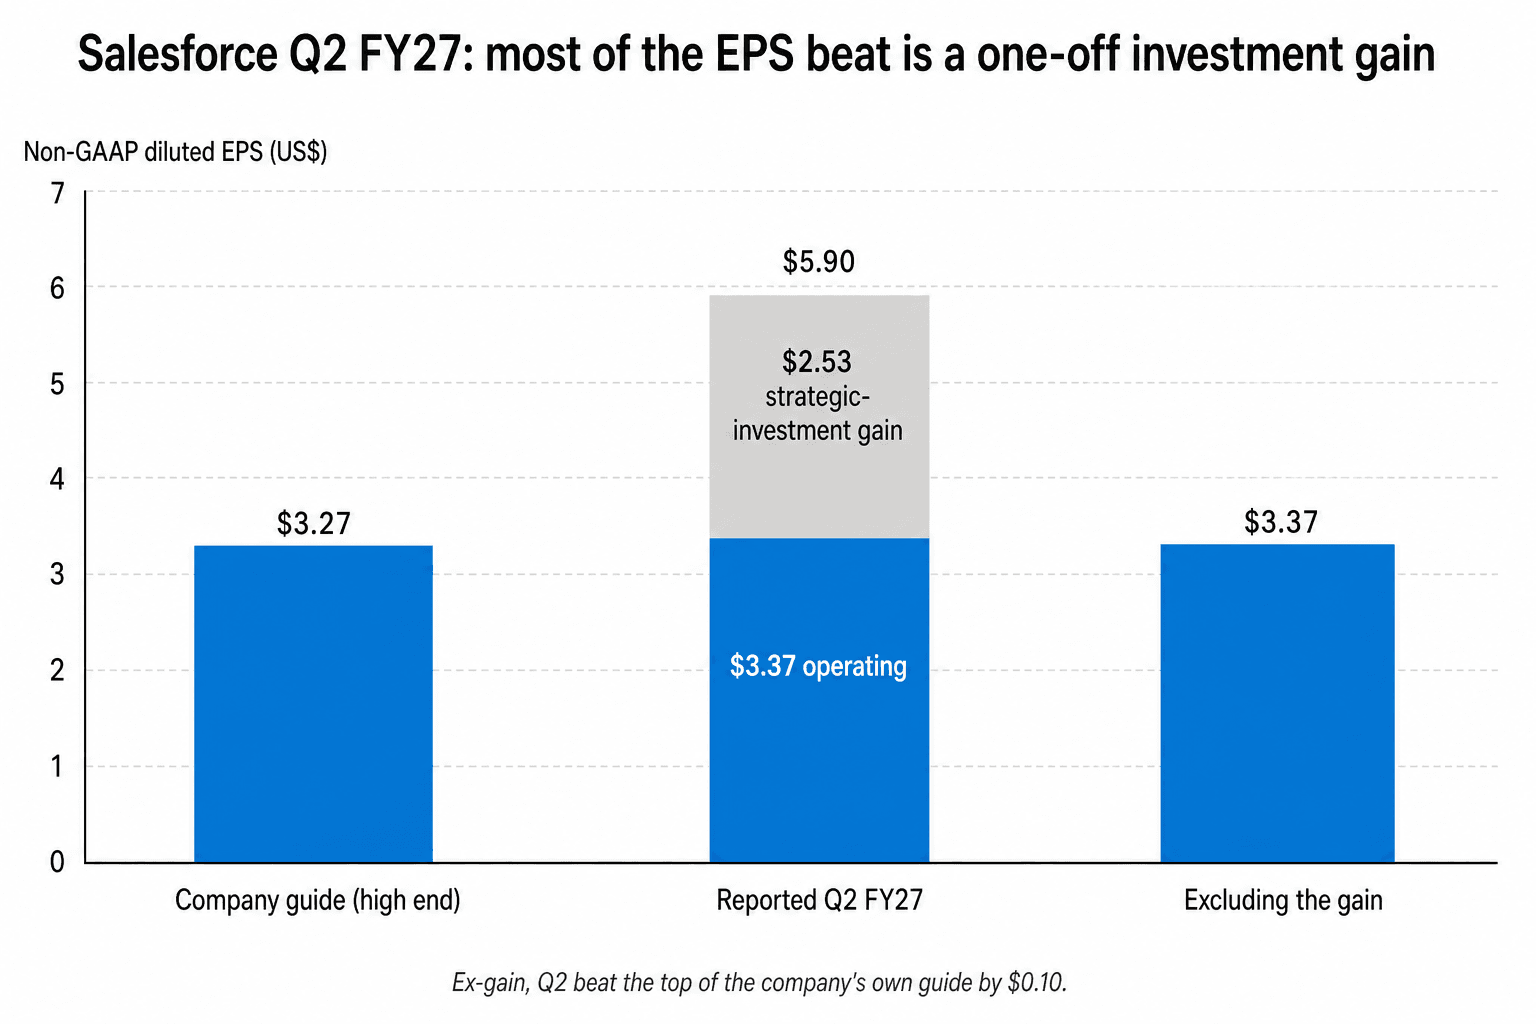
The line called "gains on strategic investments" went from $6M in the year-ago quarter to $2,613M. Salesforce does not exclude that from its non-GAAP results, but it does publish what it is worth per share: $2.53 of non-GAAP diluted EPS and $2.43 of GAAP diluted EPS, against $0.00 a year ago.
Subtract the company's own figures and the picture inverts:
| Q2 FY27 diluted EPS | Q2 FY26 | Q2 FY27 | YoY |
|---|---|---|---|
| Non-GAAP, as reported | $2.91 | $5.90 | +102.7% |
| Non-GAAP, excluding the disclosed gain | $2.91 | $3.37 | +15.8% |
| GAAP, as reported | $1.96 | $4.29 | +118.9% |
| GAAP, excluding the disclosed gain | $1.96 | $1.86 | −5.1% |
Those are not an outside analyst's adjustments. They are the reported numbers minus the per-share impact Salesforce itself printed.
At $3.37 the quarter still beat the top of the company's guide by ten cents. That is real, and it is a dime, not a blowout. The gain is driven mostly by the stake in Anthropic, begun as a $50M investment in 2023. Marc Benioff was unusually direct about the loop on the call: "take the value of our anthropic stock. That's been like, half our value of our… Forget our cash flow or our customer base. That's why I said, 'Robin, go try to buy as much back as much Salesforce stock as you can.'"
Which is the second thing flattering the per-share line. That $25 billion accelerated share repurchase, funded with new debt, took diluted shares from 962M to 821M, down 14.7% year over year. Smaller denominator, bigger EPS.
Revenue grew 11%. Operating income grew nothing.
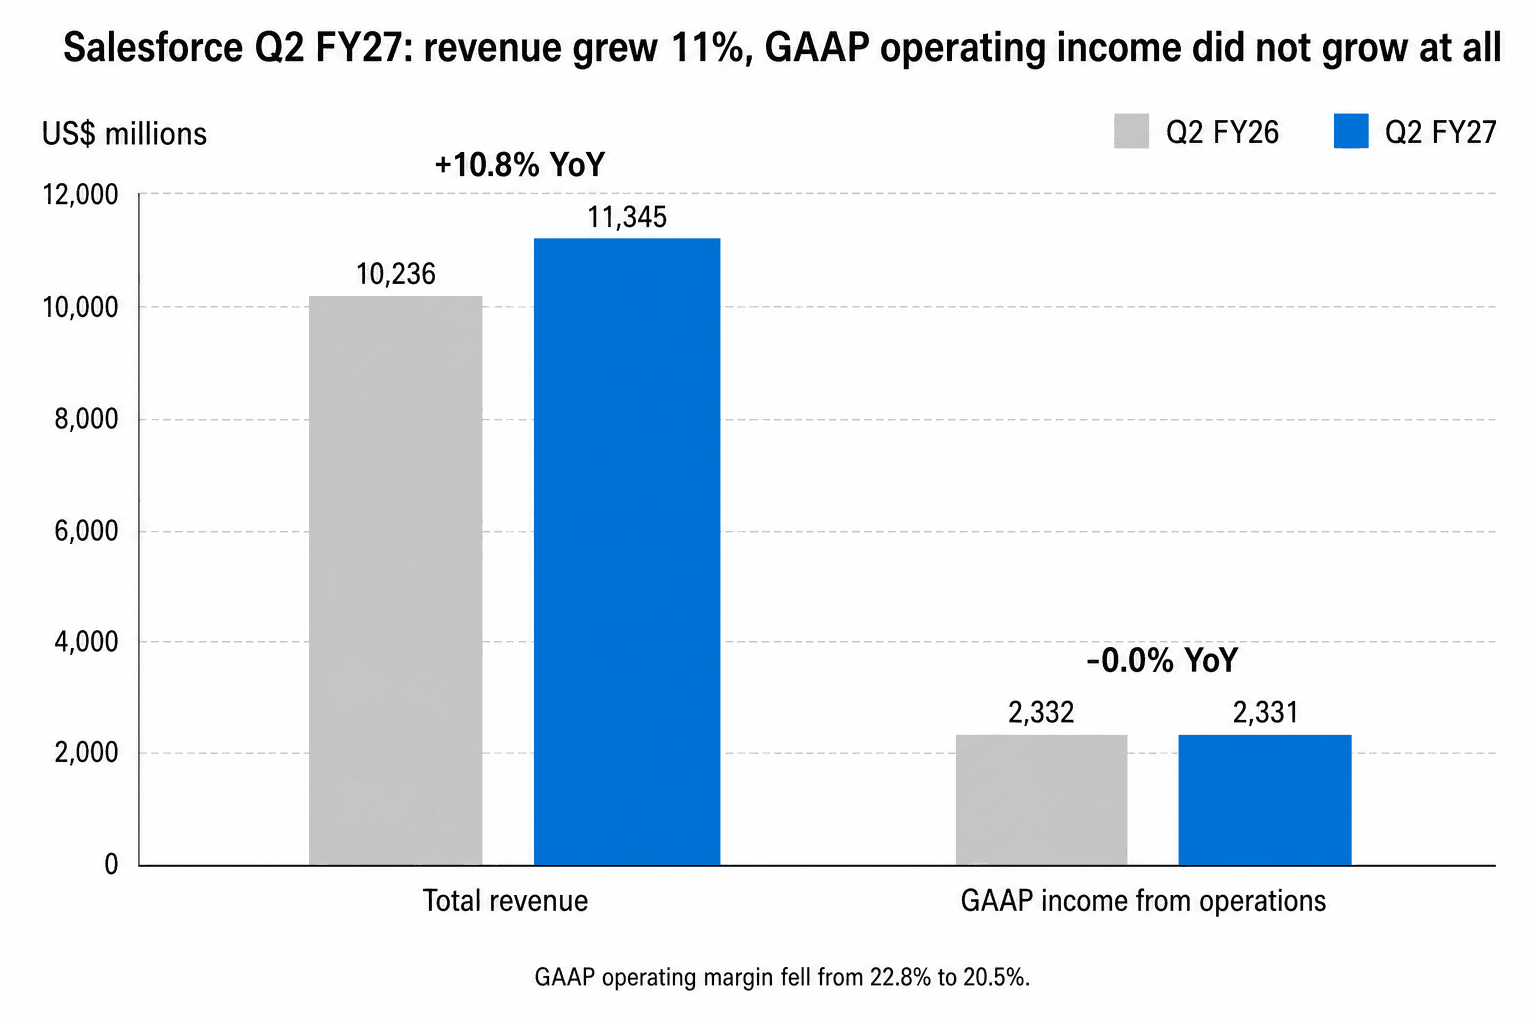
GAAP income from operations was $2,331M. A year earlier it was $2,332M. Revenue over the same span rose 10.8%.
GAAP operating margin fell 2.3 points to 20.5%. Non-GAAP operating income grew 10.3%, marginally slower than revenue, so non-GAAP operating margin fell too, by 0.2 points to 34.1%. That is the first year-over-year non-GAAP margin contraction in the eight-quarter series, and it ends the margin-expansion streak management had been citing.
The cost side explains it. Subscription cost of revenue grew 22.9% against subscription revenue of 11.7%, taking subscription gross margin to a series-low 81.3% on Informatica intangible amortisation and AI compute. R&D rose 13.9%. Sales and marketing rose 12.1%, essentially in line with revenue, which means no operating leverage at all. Restructuring of $94M was the fifth such charge in eight quarters.
Below the operating line, the buyback debt shows up: interest expense went from $67M to $473M. Set the investment gain aside and the arithmetic is unforgiving. Non-GAAP operating income added $363M year over year, interest expense took $406M of it and lower other income another $54M. The debt raised to shrink the share count consumed the entire year's operating profit growth.
Neither Benioff's "strong margin performance" nor CFO Robin Washington's recitation of "34.1% and 20.5%" acknowledged that both are down year over year. No analyst asked.
Forty-one percent of the growth was bought
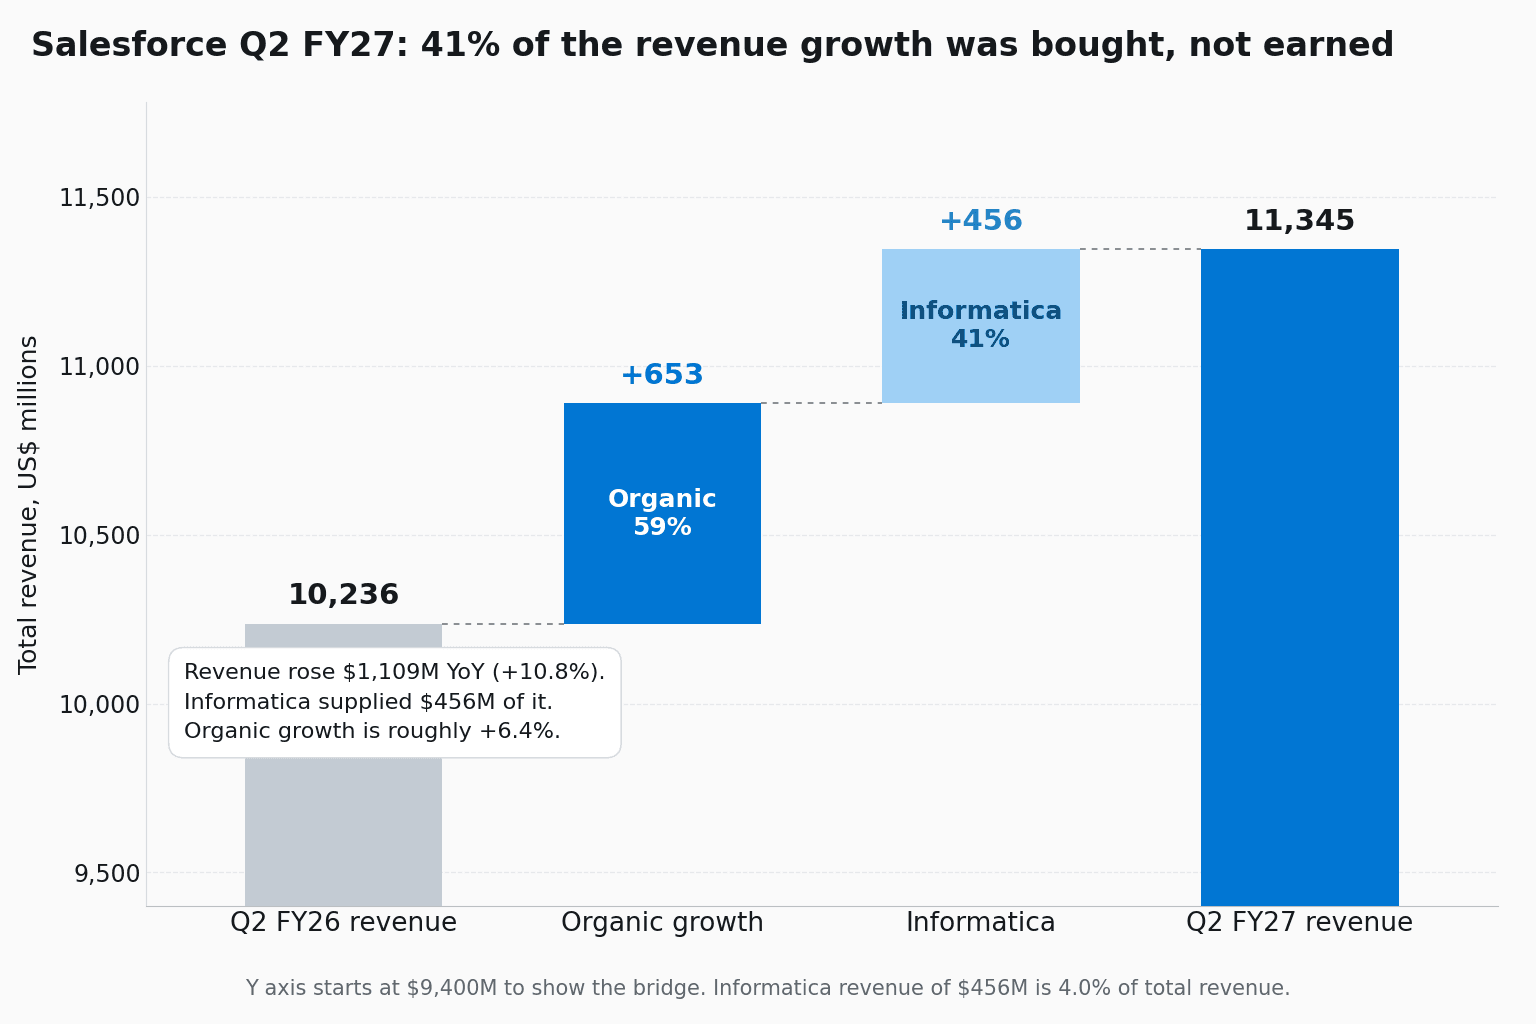
Revenue of $11,345M landed at the top end of guidance. Informatica supplied $456M of the $1,109M increase, so 41% of the growth was acquired. Ex-Informatica, organic growth is roughly 6.4%.
The product split says the same thing. Salesforce now reports subscription revenue in two buckets. Agentforce Apps, the Sales, Service, Marketing, Commerce and Slack core that is about two-thirds of subscription revenue, grew 7.6% year over year nominal and decelerated from 8.9% the previous quarter. Data 360, Headless Platform and Other, where Informatica, MuleSoft and Tableau sit, grew 20.3% nominal. (The company's own constant-currency prints for those two lines are 8% and 20%.)
The full-year guide went to $46.1–46.4 billion from $45.9–46.2 billion, and Washington decomposed the $200M raise herself: "$100 million of organic growth, $200 million from the pending Contentful and Fin acquisitions, and $100M FX headwind." The organic raise is $100M on a $46 billion base.
The EPS guide raise is the same trick in a longer frame. Full-year non-GAAP EPS went up $2.61 against a Q2 investment benefit of $2.53 a share already banked, and Salesforce states that its projected EPS "assumes no change to the value of our strategic investment portfolio." Guidance for the rest of the year barely moved on an operating basis. The GAAP operating margin guide was actually cut 50 basis points, to 20.1%.
The number that was genuinely good
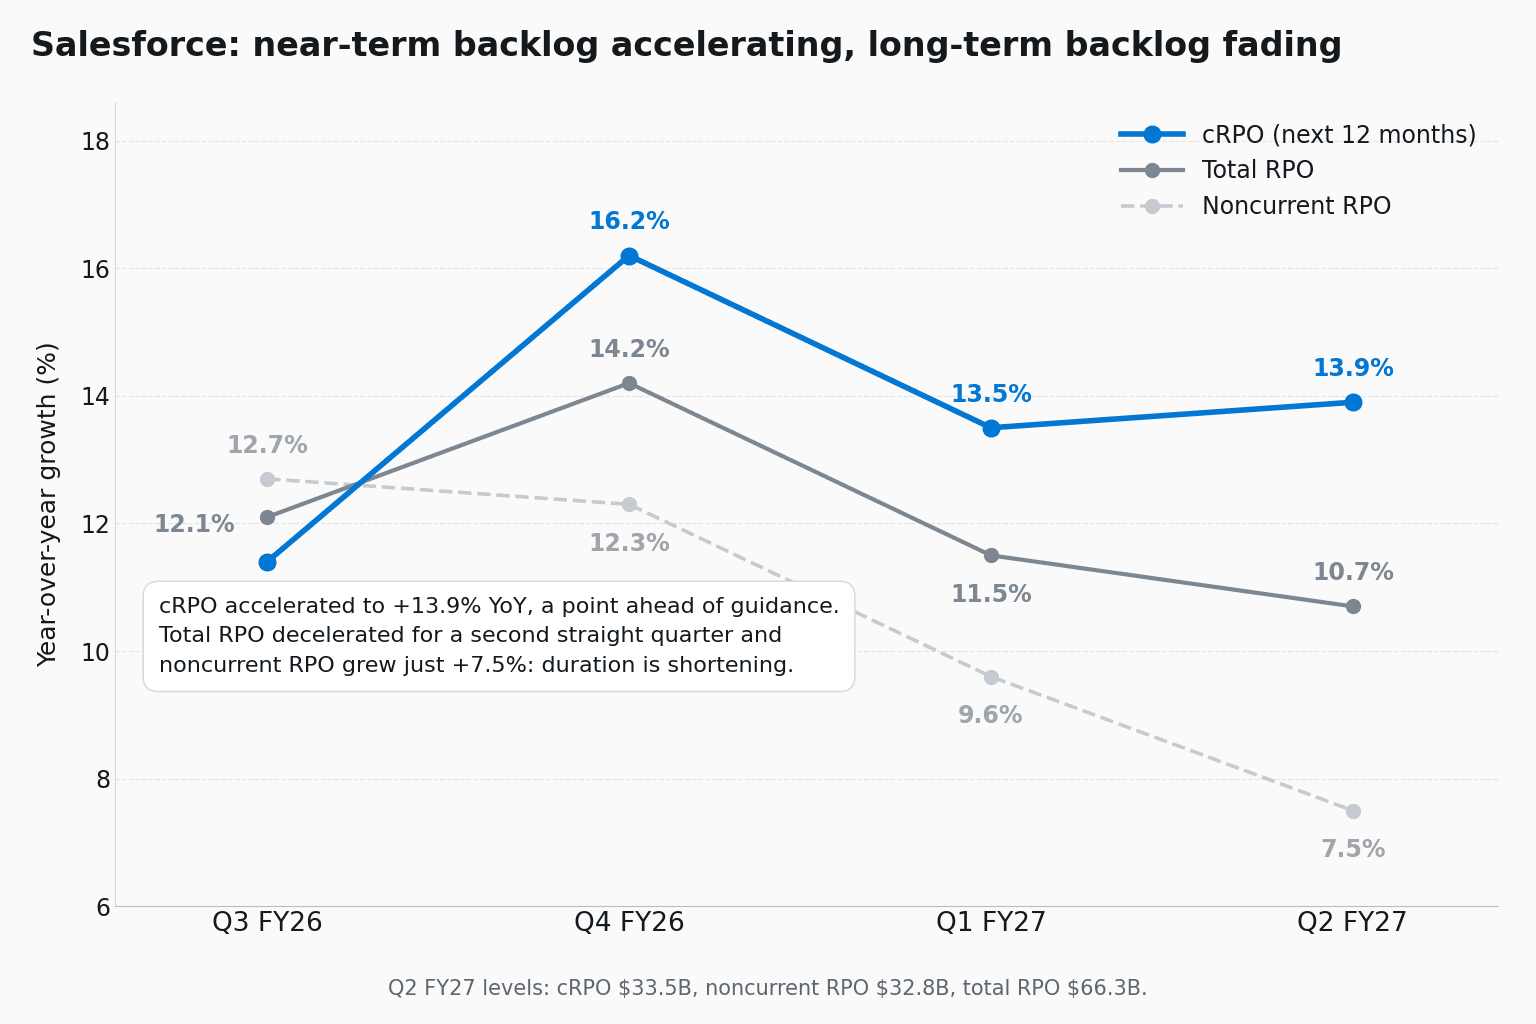
cRPO (current remaining performance obligation, contracted revenue expected to be recognised over the next 12 months) came in at $33.5B, up 13.9% year over year on a nominal basis. Salesforce prints 14%, both as reported and in constant currency, and management said it landed a point ahead of guidance.
The important word is accelerated, from +13.5% the previous quarter. This is the forward-demand indicator the market actually trades on, and the bear thesis of 2026 was that it would roll over as AI ate seat-based software. It did the opposite. Filed attrition held at approximately 8%, unchanged for eight straight quarters. Agentforce ARR crossed $1.5B, combined Agentforce and Data 360 ARR reached about $3.9B, and customers ran 3.2 billion agentic work units in the quarter. Miguel Milano said Agentforce bookings doubled year on year, and that half of them "came from customers refilling the tank."
That is a real signal and the stock was right to respond to it.
One asterisk sits on the same chart. Total RPO grew only 10.7% and decelerated for a second consecutive quarter, and noncurrent RPO grew just 7.5%. cRPO is now 50.5% of total RPO, the highest in the series, which is the arithmetic signature of shortening contract duration at the long end. Management says contract terms are lengthening. Both can hold if new agentic business is written on shorter terms than the multi-year licences rolling off, but it is the thing to check in Q3.
The Street chased and still fell behind
More than twenty dated sell-side actions landed on 27 August. Almost all raised targets: Raymond James to $310, Truist, Jefferies and BTIG to $300, and Needham held the Street-high $400. What matters is who did not upgrade. Eight houses lifted the target and left the rating alone, including RBC at Sector Perform, UBS and Citi at Neutral, Morgan Stanley and Wells Fargo at Equal Weight. The multiple moved, the model did not. Wells Fargo's Michael Turrin made the most falsifiable objection, that organic exit growth is still below the level required to hit the long-term targets. Bank of America's Tal Liani stayed at Underperform and $160.
The consensus price target now sits at $261.15 against a $252.05 close, about 3.6% of implied upside, versus roughly 32% a month ago.
Attribute the tape carefully, though. NVIDIA, CrowdStrike and Okta all reported the same evening and closed +8.74%, +20.50% and +28.63%, and the software ETF IGV closed +7.74%. Part of the day was a sector re-rate rather than a verdict on Salesforce alone. Workday, the closest structural analogue, managed +1.48%.
What to watch
Whether operating profit starts growing again. Eleven percent revenue growth with flat operating income is not a shape a company can hold for long, and the Dreamforce investor day on 16 September is where the long-term model gets restated.
Whether cRPO holds near 14% in Q3. The guide is approximately 14% and explicitly excludes Contentful and Fin, so there is nowhere for an acquisition to hide.
And whether anyone keeps talking about the portfolio. Guidance assumes the Anthropic mark never moves again. It will.
Salesforce had a good quarter. It just wasn't a $5.90 one.