Wiwynn Q1 2026: Gross Margin Inflects After Eight Quarters Down, ASIC + GPU Dual Engine Takes Shape
Wiwynn (6669.TW) held its Q1 2026 analyst meeting on the afternoon of 2026-05-15. The headline numbers are pretty: revenue NT$276.508B, net income NT$14.114B, EPS NT$75.95 — all all-time Q1 records, +62% YoY revenue, +44% YoY EPS. But the YoY numbers are not what's worth reading. Two structural lines are.
Gross margin moved up 32 bps. First sequential improvement in eight quarters.
Wiwynn's gross margin has been a one-way line since 2024: 9.41% (2Q24) → 9.05% → 9.18% → 8.70% → 8.40% → 7.80% → 7.23% (4Q25). The mechanics are simple: AI server revenue expands, GPU and memory pass-through costs land in COGS, and the same dollar of gross profit gets spread over a larger revenue denominator.
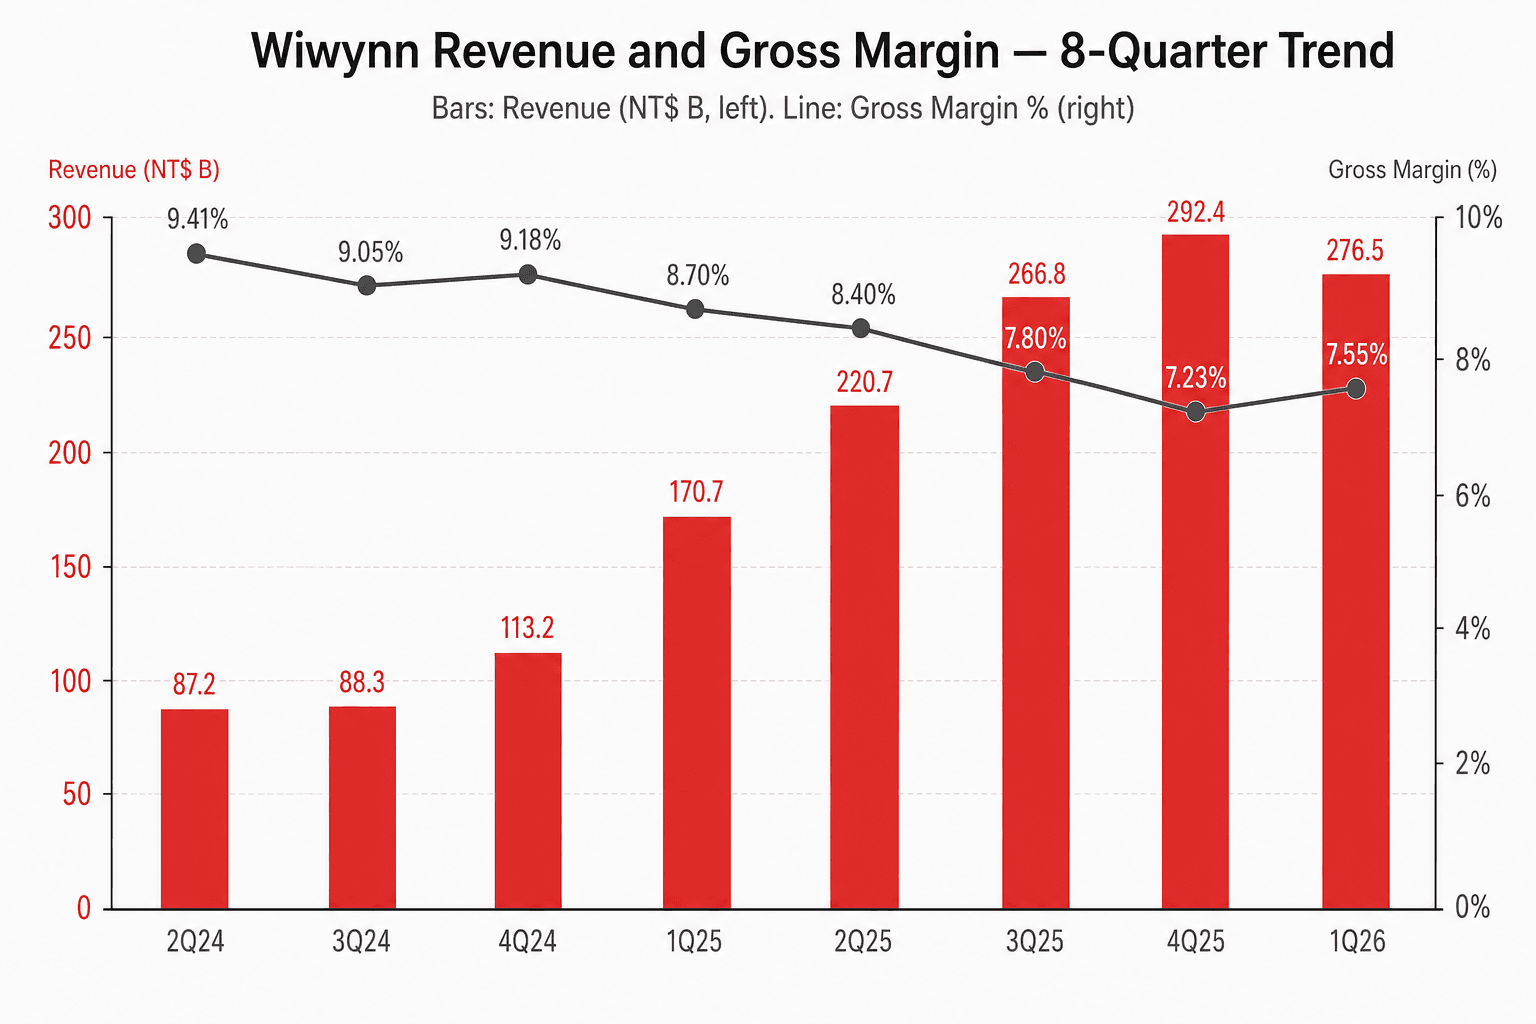
1Q26 gross margin 7.55%, +32 bps QoQ — the first structural inflection signal in Wiwynn's AI cycle. Three sources: (1) a richer ASIC rack mix carrying more value-add per unit than reference GPU racks; (2) cleaner working capital after a 4Q25 inventory pull-in; (3) the memory consignment model doesn't take effect until April, so 1Q26 still reflects the old gross-up regime.
The cleaner read is actually the operating margin: 5.63% → 6.31%, +68 bps QoQ — 36 bps faster than gross margin moved. Wringing +68 bps OPM out of a quarter where revenue printed -5.45% QoQ is opex discipline, not operating leverage.
ASIC + GPU dual engine. This time it's not just PR.
Wiwynn has been using the phrase "ASIC + GPU dual engine" on every call for a few quarters. 1Q26 is the first quarter with external validation that turned the slogan into fact.
Two specifics from the prepared remarks and the broker reads:
- AWS Trainium 2 keeps ramping; Trainium 3 (T3) enters mass production in H2 2026. This is the single biggest catalyst on the customer roadmap — T3 is a step-function lift to Wiwynn's ASIC line.
- GPU rack-level participation has expanded beyond ASIC-only. Wiwynn is now in the Oracle VR200 (NVIDIA Vera Rubin) platform supply chain and participates in AMD MI-series related projects. Goldman Sachs's 2026-05-11 note framed it as "from ASIC-only to rack-level GPU AI systems" — and upgraded the stock from Buy to Top Pick.
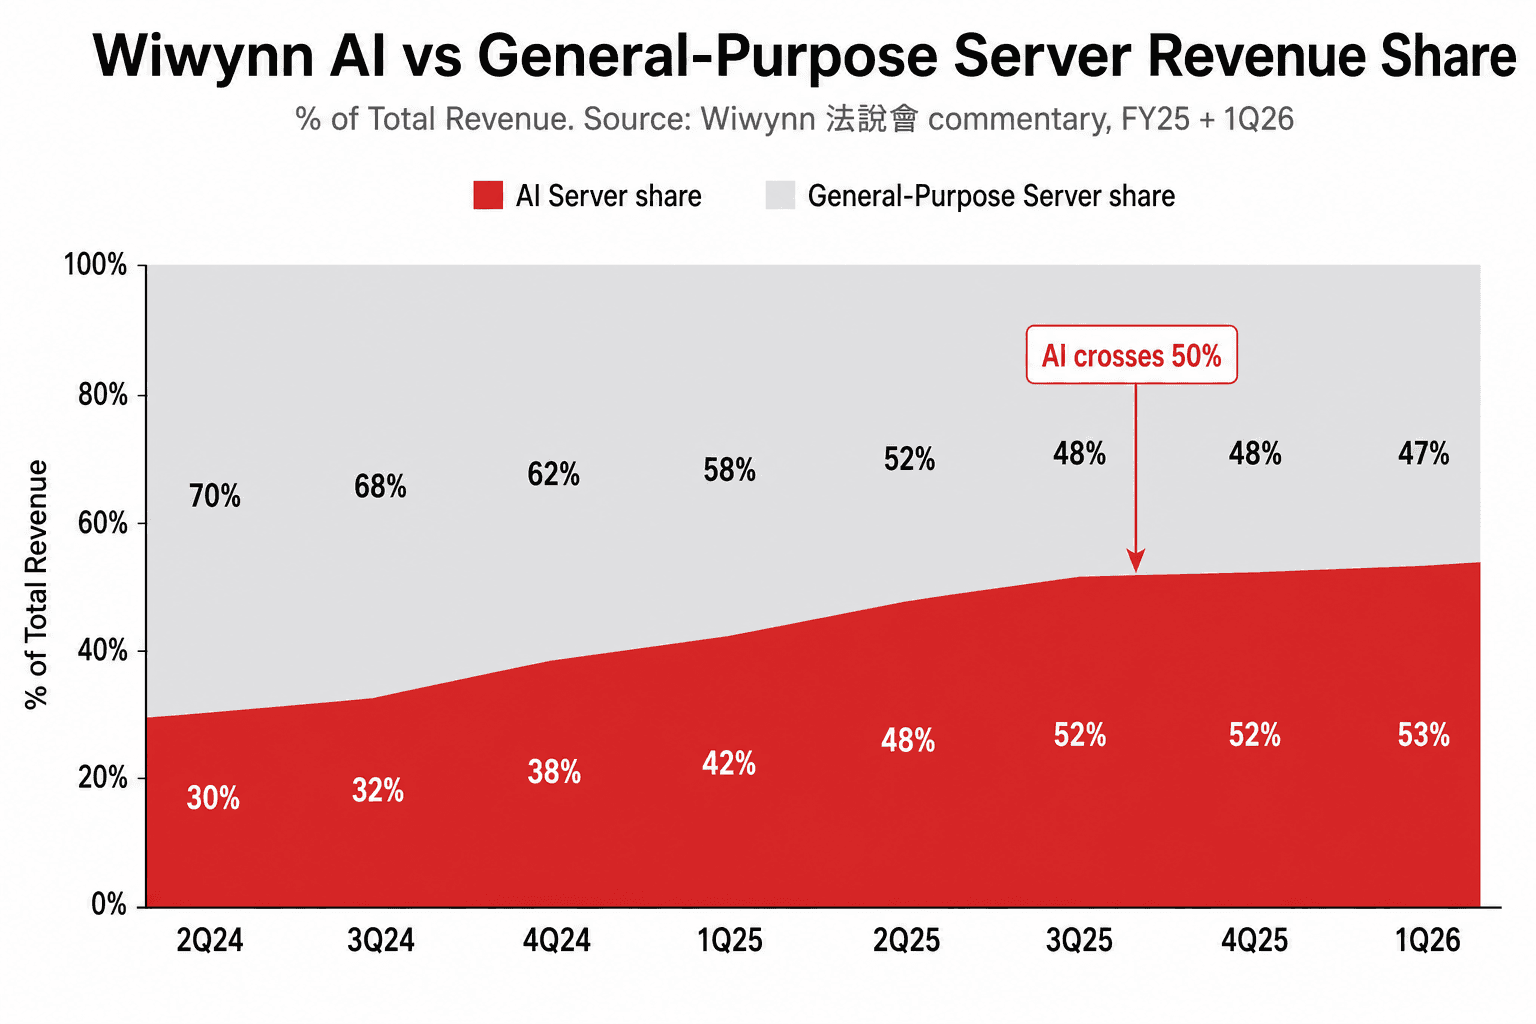
ASIC share of AI revenue drifted from ~75% (1Q25) to ~63% (1Q26); GPU rack share moved from 25% to ~37% over the same window. That 12-percentage-point shift is the cleanest evidence of Wiwynn's AI multi-axis story.
Customer concentration came down. But AWS is doing all the work.
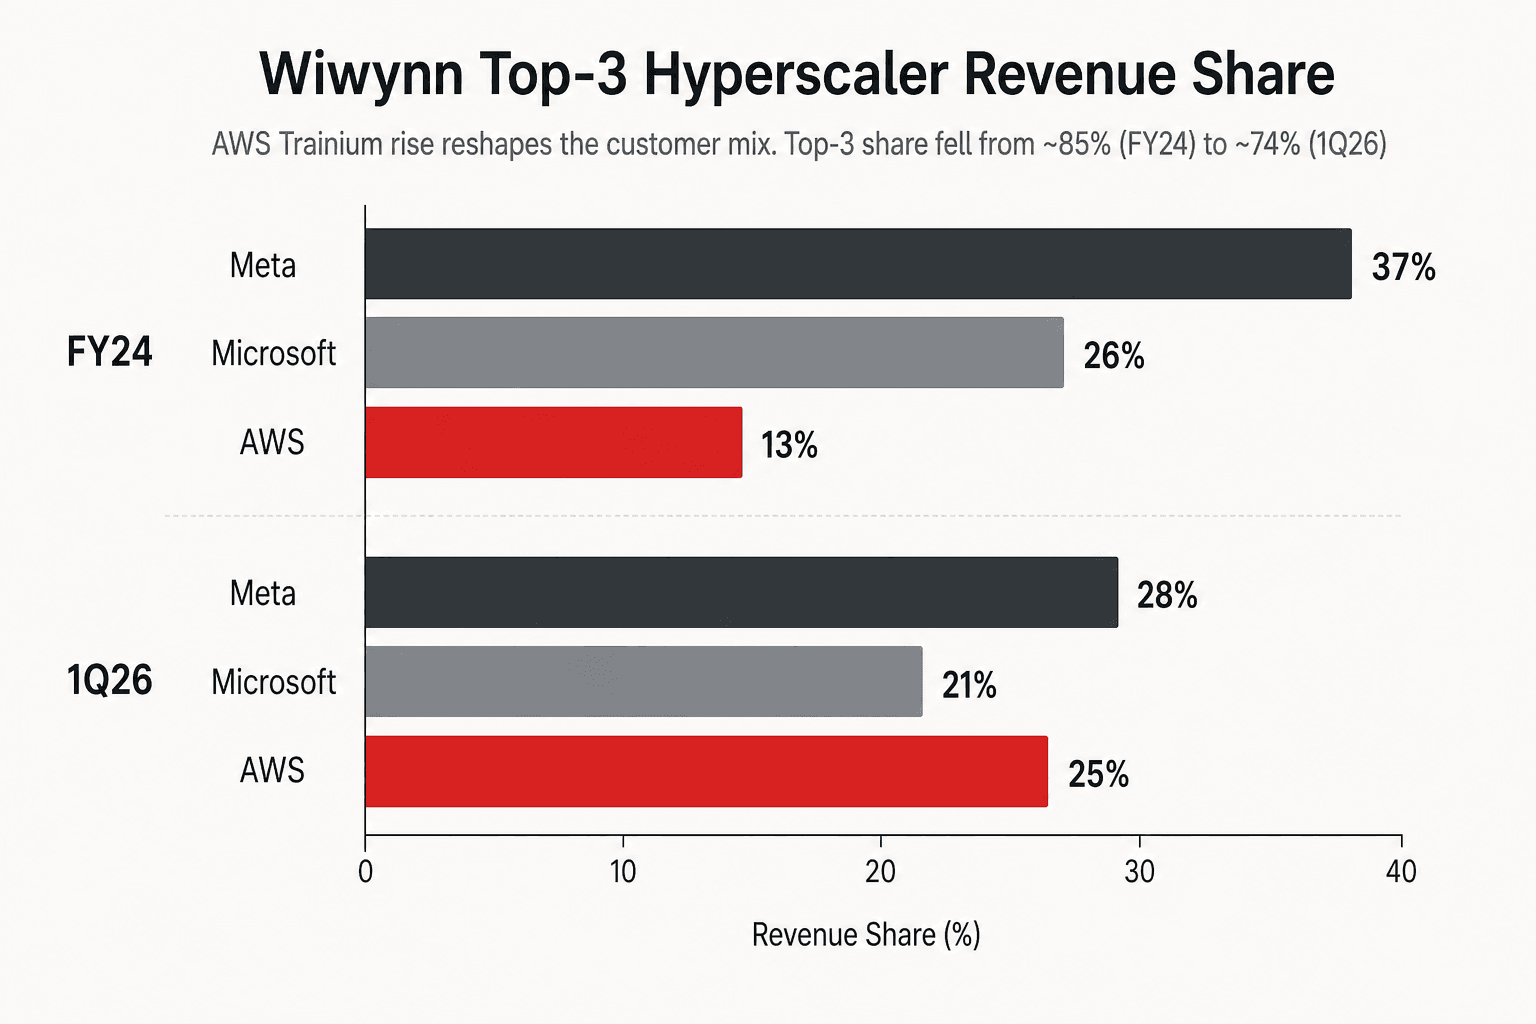
Wiwynn's traditional knock has been Top-3 customer concentration (Meta + Microsoft + AWS) above 85% — with Meta alone at 35–40%. That structure has visibly loosened: Top-3 combined is now ~74%, and "Others" (Oracle VR200, AMD MI, Tier-2 CSPs) has doubled to ~26%.
Read it closer and the "concentration decrease" is really a swap: Meta from 37% to 28%, Microsoft from 26% to 21%, AWS from 13% to 25%. The Trainium line is the fastest-growing customer slice in FY26. Wiwynn is trading Top-3 concentration for AWS concentration — structurally more diversified, but the single-program-execution risk hasn't actually gone away.
That -16% MoM in April is not bad news.
April 2026 monthly revenue NT$82.731B, MoM -16.14%, YoY +29.67%. The optical decline is the first month of the memory consignment model:
| Model | Optical Revenue | Underlying Rack Shipments | Absolute Gross Profit | Working Capital |
|---|---|---|---|---|
| Old (memory gross-up) | high | same | same | heavy |
| New (consignment) | low | same (April actually up MoM) | slightly higher | materially lighter |
Management's framing is direct: full-year profit unaffected by the business model change; full-year shipment volume guide of double-digit YoY growth unchanged. Which means Q2 and Q3 optical revenue will keep "declining," while absolute profit dollars rise sequentially.
This is the easiest part of the print to misread. Look at EPS, look at absolute earnings, don't look at the revenue growth rate.
US$500M one-shot into the Americas.
The board approved a US$500M (~NT$15.69B) capital injection into Wiwynn International Corporation alongside the print — the largest single overseas commitment in company history, earmarked specifically for Mexico + US (Texas) capacity expansion.
For comparison: Quanta announced US$800M of overseas injection on its own analyst meeting day (2026-05-14). Taiwan's AI server CM cohort is moving in lockstep on "in-region delivery" — and the size of these commitments suggests customer pipeline visibility extends well beyond 2027.
So why only +7.7% from the analyst meeting?
From the 2026-05-07 print to the 2026-05-15 close, Wiwynn gained +7.7% cumulatively (vs. TAIEX +1.8%, sector ~+4%) and printed a fresh all-time high. Goldman Sachs upgraded to Top Pick. Yuanta, Fubon, KGI, President all raised target prices. But the market gave less than a 10% move.
Two reasons:
- The market is still digesting Q2/Q3 optical revenue "decline." Even with absolute profit rising, multiple expansion stalls when the revenue print looks like it shrank.
- Trainium concentration risk. As T3 ramps, Wiwynn's single-customer (AMZN) exposure is actually rising even as the Top-3 share falls. The bulls want to see Vera Rubin + AMD share grow as offsets before fully re-rating.
On GS's new FY26E EPS of NT$357.5, the 2026-05-15 close at NT$4,910 is ~13.7× forward P/E. On FY27E EPS NT$466.8, it's ~10.5×. Inside Taiwan's AI server cohort, that is the cheapest and the cleanest at the same time. The valuation gap is exactly what the GS Top Pick call is anchored on.
What to watch
Three events over the next four quarters decide whether the story actually holds:
- Q2 analyst meeting (mid-August 2026) — the first full quarter under the new model. Optical revenue vs absolute profit ratio will settle the read.
- AWS Trainium 3 mass production (H2 2026) — T3 shipment cadence is the ASIC engine's step function.
- Vera Rubin / GB300 supply chain participation — whether GPU rack share moves up another level.
Wiwynn's 1Q26 is the cleanest "earnings quality > headline revenue" print in Taiwan's AI server cohort this quarter. Quanta took a 314 bps YoY gross-margin hit to grab GB200/GB300 volume; Wiwynn took only a 115 bps YoY hit and lifted GM 32 bps QoQ — and also removed the memory gross-up entirely from April onward. Five things landed in one quarter: same-quarter highs, GM inflection, customer diversification, business model upgrade, overseas capacity doubling. That combination is rare in this AI cycle.