ASE Technology Q2 2026: Packaging Is the Profit Engine, and One Earnings Report Sent the Stock Limit-Up
One earnings report sent the stock limit-up
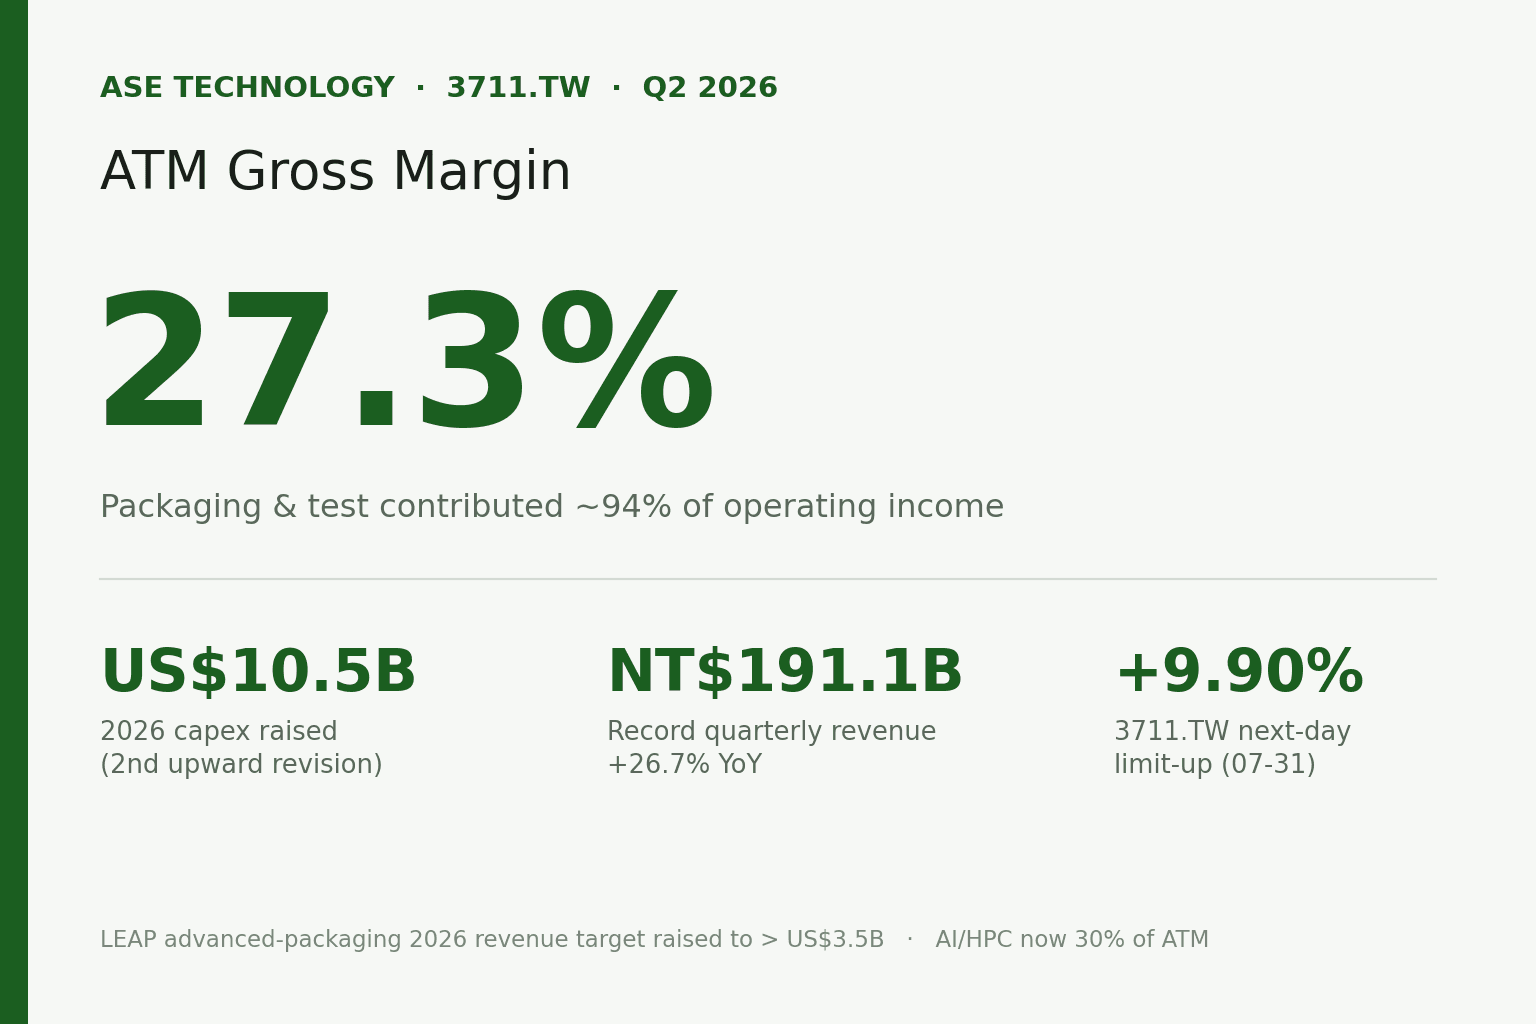
On the afternoon of July 30, 2026, ASE Technology (3711.TW) wrapped up its Q2 earnings call. The market's read was blunt: the next day, 07-31, 3711.TW gapped up and locked limit-up, closing +9.90% at NT$555 — a single price for the entire session.
When an earnings report can drive a stock to limit-up, it's usually because it made several things clear at once. What ASE laid out this time: packaging and test is the profit engine, capex has further to climb, and demand for advanced packaging is running hotter than the company itself had assumed.
The quarter: revenue at a new high
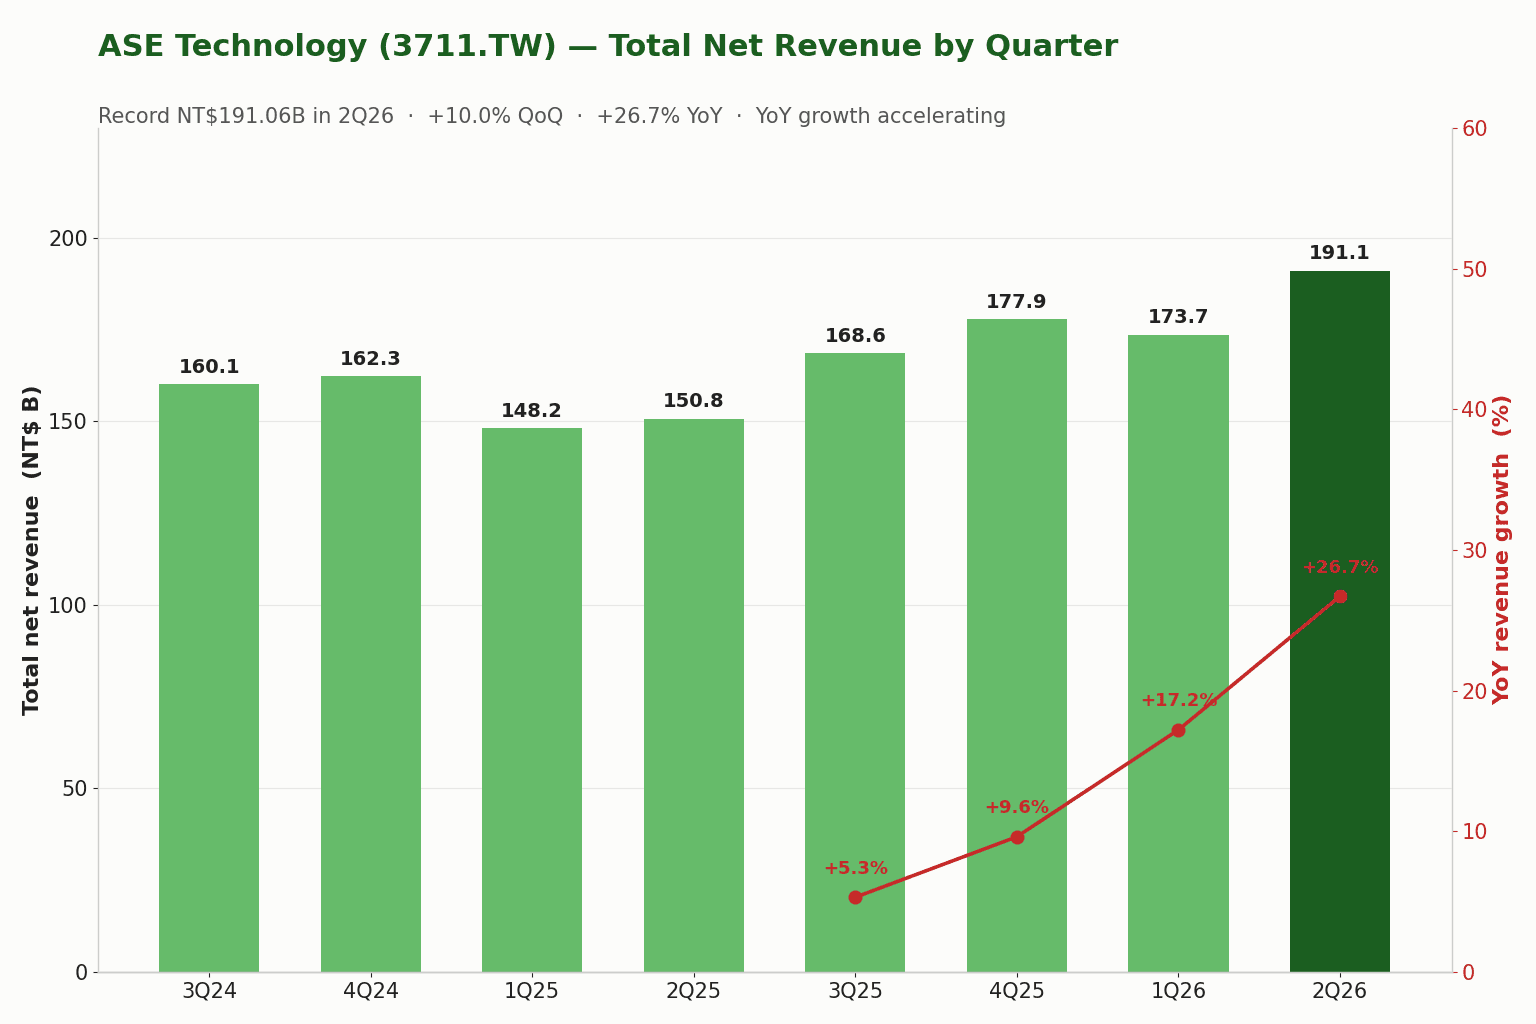
Consolidated revenue was NT$191,064M, up 10.0% QoQ and 26.7% YoY — a record for a single quarter. What deserves more attention is the slope of the YoY growth: from +5.3% in 3Q25 to +9.6% in 4Q25, +17.2% in 1Q26, and accelerating all the way to +26.7% this quarter. The −2.4% sequential dip in 1Q26 was just the usual seasonal soft patch; in Q2, AI/HPC packaging demand re-steepened the growth curve.
Packaging & test vs. EMS: nearly all the profit sits in ATM
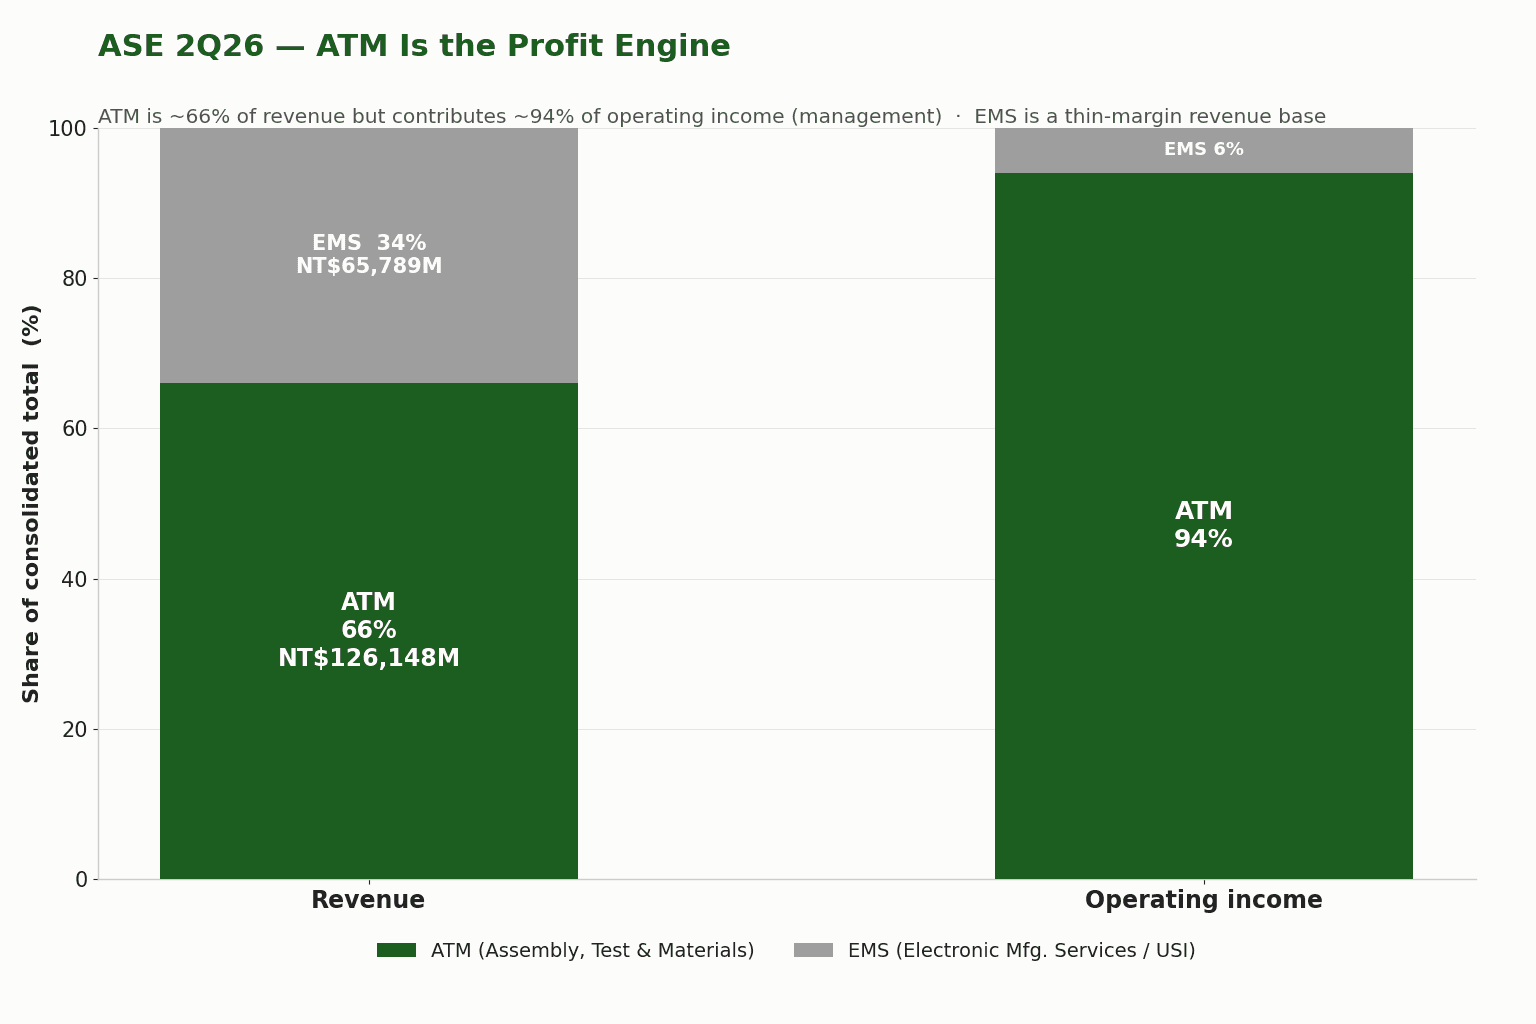
ASE runs two businesses: packaging & test (ATM, spanning assembly, test and materials) and EMS (electronics manufacturing services, i.e. USI). This quarter ATM revenue was NT$126,148M and EMS revenue NT$65,789M. Break out the mix and one gap stands out: ATM is about 66% of consolidated revenue, yet it delivered roughly 94% of operating income.
The reason is gross margin. ATM ran at 27.3%; EMS at just 8.9%. EMS is a large but thin revenue base, while the segment that really sets the group's profitability is packaging & test. With ASE, the point isn't how big total revenue is — it's how well the packaging business earns.
ATM gross margin: closing in on the structural ceiling
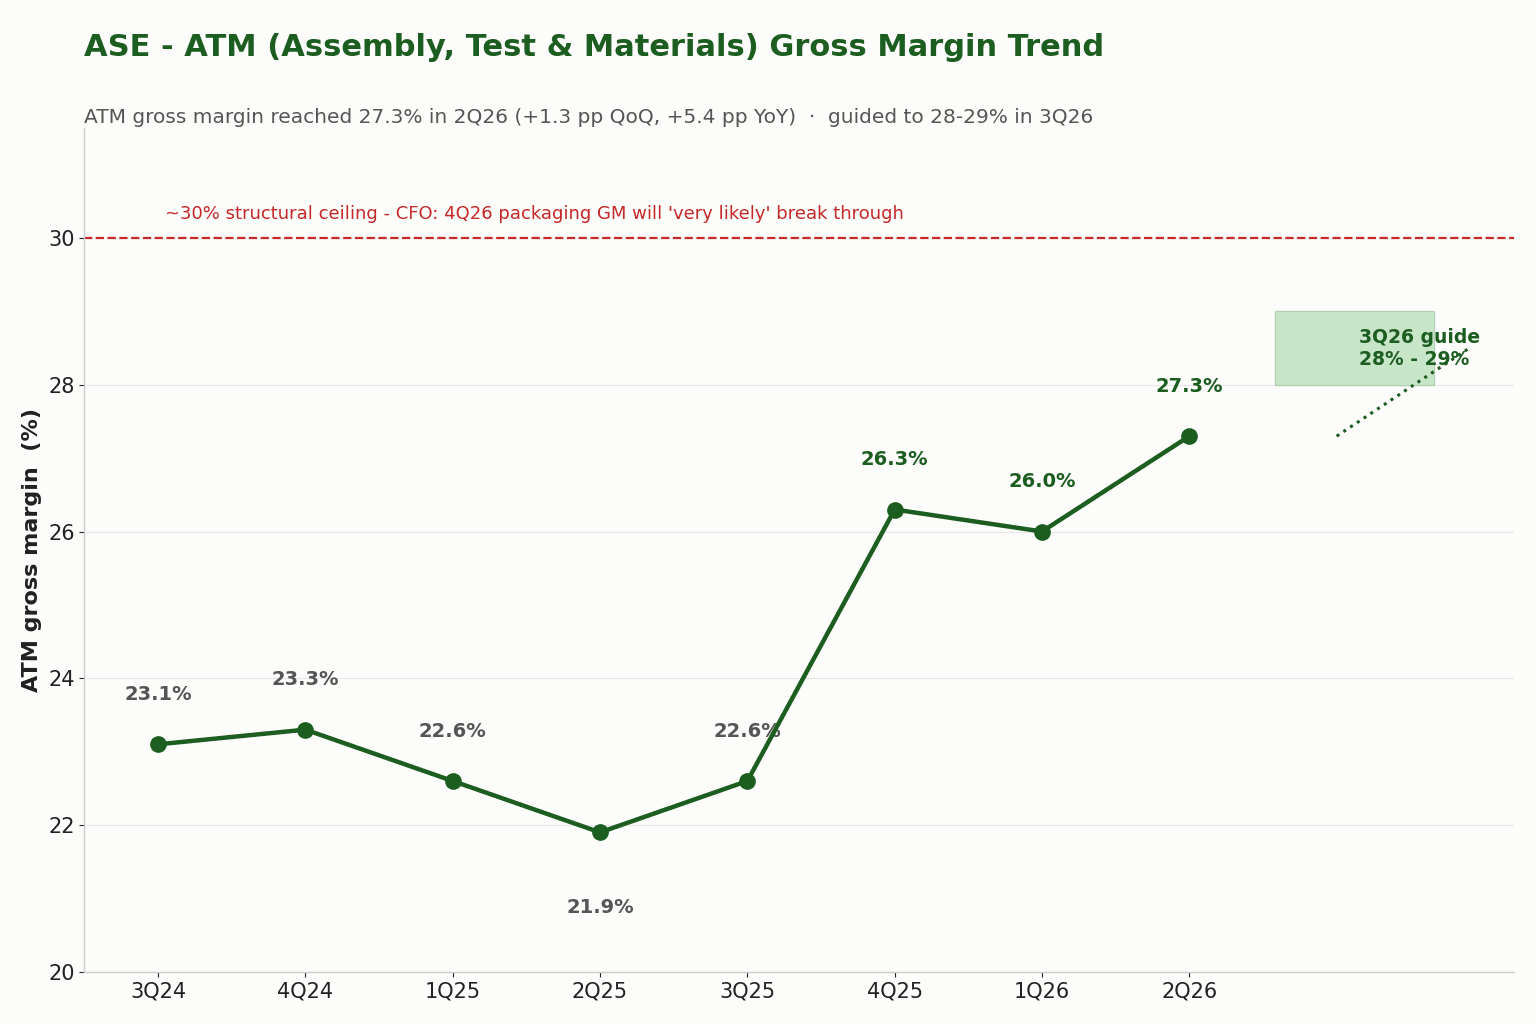
ATM gross margin of 27.3% — up 1.3pp QoQ and 5.4pp YoY — is the engine lifting the blended gross margin (21.0%) for a fourth straight quarter. CFO Joseph Tung stressed this wasn't built on any single factor: utilization and operating leverage, a rising high-margin LEAP mix, line automation, and a falling expense ratio all pulling together.
The forward look is even more telling. The Q3'26 ATM gross-margin guide is 28–29%, and Tung went further, saying 4Q26 packaging & test gross margin is "very likely" to break through the current structural ceiling of around 30%, after which the company will raise its long-term structural margin range. In other words, management itself thinks the ceiling is about to move up.
AI/HPC and capex: the bottleneck is capacity, not demand
The cleanest AI signal is Computing (AI/HPC) as a share of ATM revenue: 24% a year ago, 27% last quarter, and 30% this quarter. Over the same span, communications fell from 46% to 41% — the mix is tilting toward high-performance computing.
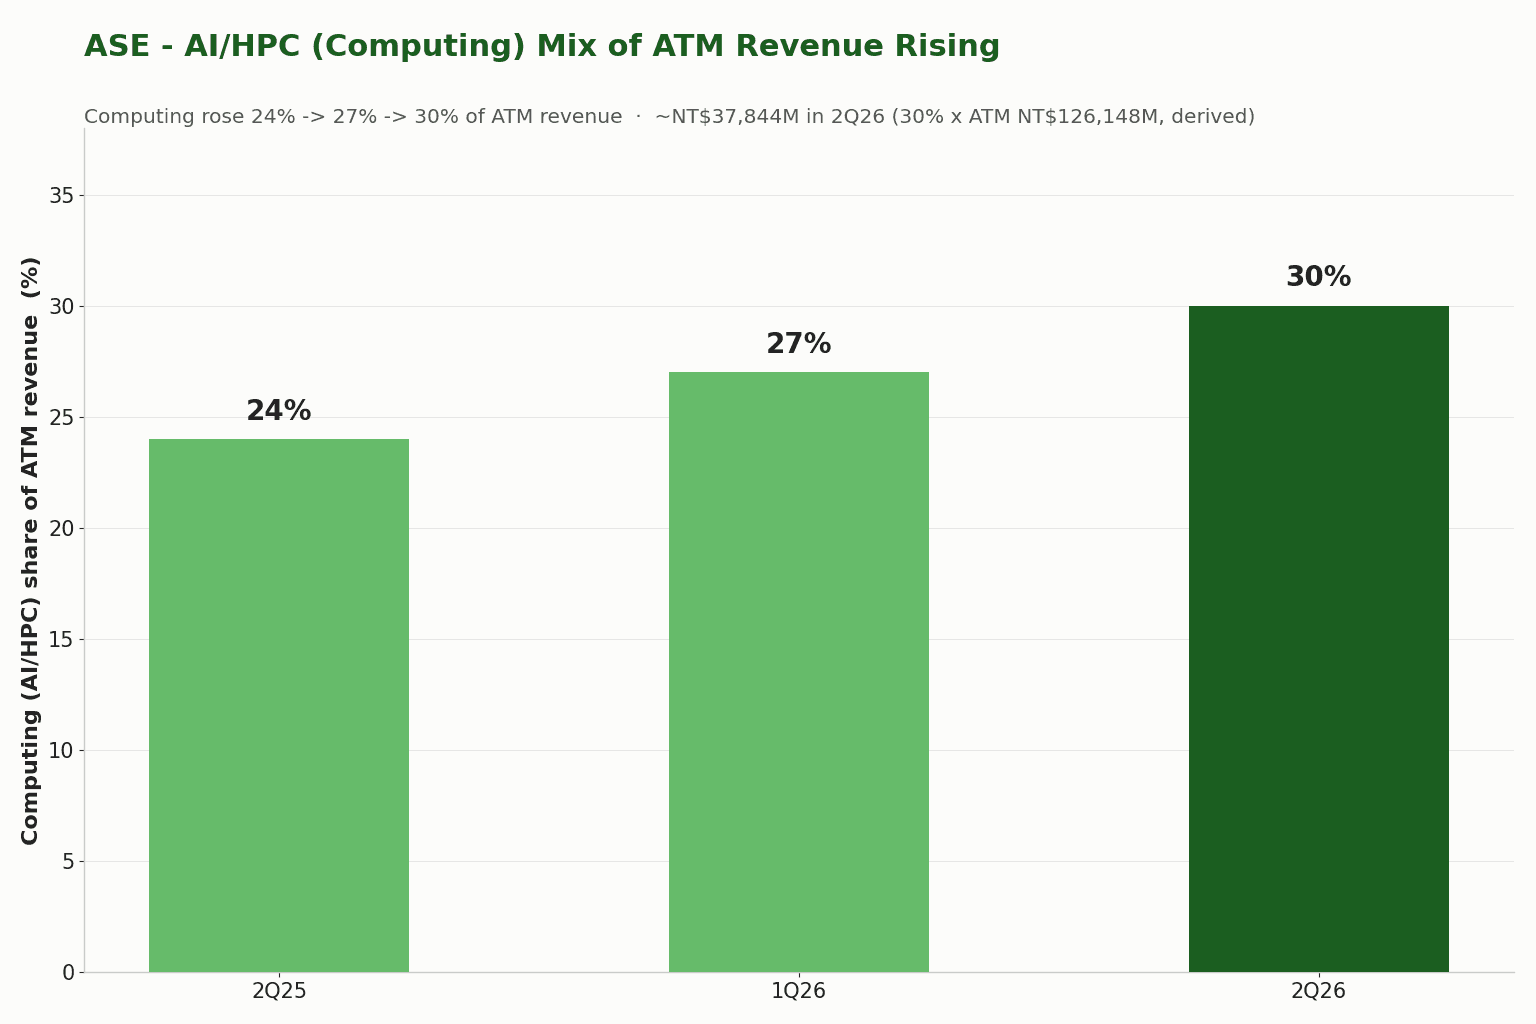
Behind that line is LEAP advanced packaging. ASE raised its 2026 LEAP revenue target by about 10%, to more than US$3.5B, and called for another doubling in 2027. Capex spiked in step: NT$79,849M in the quarter, up 81% QoQ, with full-year 2026 raised a second time to about US$10.5B (from around US$8.5B), roughly 70% of equipment spending going into LEAP (Reuters, 2026-07-30).
COO Tien Wu's framing is clear: ASE now sits in a position where demand isn't the constraint — capacity is. His point: guiding Q3 up 11–13% means adding 11–13% of capacity to match. The near-term ceiling on revenue is the pace of tool installs, fab construction and line qualification, not order intake. The shift shows in the capital structure too: wire-bonder counts fell YoY while tester counts rose more than 20% YoY — money is flowing out of traditional wire bonding and into test and advanced packaging.
Backing out the one-off non-operating items
Net income grew 180.1%, outrunning the 107.3% rise in operating income — a gap worth flagging. Non-operating income totaled NT$4,566M this quarter versus just NT$668M in the prior one. The bulk of the difference is a +NT$3,637M hedging FX gain plus equity-investment valuation gains (Joseph Tung cited roughly NT$4.2B). Layer on a 2Q25 base depressed by FX and valuation swings in the other direction, and the YoY rate is amplified further.
Once you strip that out, the underlying business still looks great: operating margin of 11.1%, ATM operating margin of 15.7%, basic EPS of NT$4.80 and diluted EPS of NT$4.61 — the second-highest single-quarter profit on record (the 4Q21 peak included a one-off disposal gain, so on an operating basis this quarter was in fact a new high; see Anue's earnings coverage). Anyone extrapolating off "net income up 180%" alone is building the next quarter's estimate on a base that carries one-off gains.
Q3 guidance: revenue steps up again
The Q3'26 guide is just as strong: consolidated revenue up 21–22% QoQ, blended gross margin of 20.5–21.5%, and ATM revenue up 11–13% QoQ. The roughly 40% QoQ jump in EMS looks dramatic, but it's mainly the pass-through of higher memory and component prices; normalized, it's ordinary seasonality with an operating margin of about 3.7–3.8%. Revenue momentum isn't in question — the focus comes back to how high gross margin can go.
Market reaction and analysts
The price action landed the day after the call. On 07-31, 3711.TW gapped up and locked limit-up +9.90% at NT$555 on volume of only about 7.5M shares, with OHLC all at the same price — the classic "limit-up locked shut, buy orders can't get filled" pattern. The prior night's US ADR (ASX) had already moved, closing +11.73% and adding another +4.73% after hours (stockanalysis.com).
Worth noting: that day was a V-shaped rebound across the whole semiconductor complex — TSMC, King Yuan Electronics, Sigurd and Powertech all pushed toward limit-up too — while 3711.TW had already corrected about 30% from NT$727 between 07-02 and 07-29. So part of the limit-up was the broad-market bounce, and part was the force of the report itself. The counterpoint is US peer Amkor, whose stock went the other way on its own soft guidance, underscoring ASE's heavier exposure to the AI/LEAP theme.
Analysts pointed uniformly higher. Five domestic brokerages set price targets above NT$700 across the board, with foreign houses in a roughly NT$628–800 range and a Japanese broker at the top of the range at NT$800 (Commercial Times, 2026-07-31).
What to watch next
Three things worth tracking. First, whether 4Q26 packaging & test gross margin really breaks 30%, and where the company resets its structural range. Second, whether capex gets revised up again; US$10.5B is already the second increase this year. Third, whether the LEAP doubling in 2027 and the rising Computing mix can carry into 2027 and 2028 — that's the core narrative holding up the valuation.
To close in a line: nearly everything ASE earned this quarter is going straight into building more advanced-packaging capacity. The market isn't questioning packaging's earning power; the bet is how long AI demand can sustain the capacity now going into the ground.