Alchip Q2 2026: N3 Ramp Lifts Revenue 82.6%, EPS Hits Record
The ramp everyone waited three quarters for finally arrived
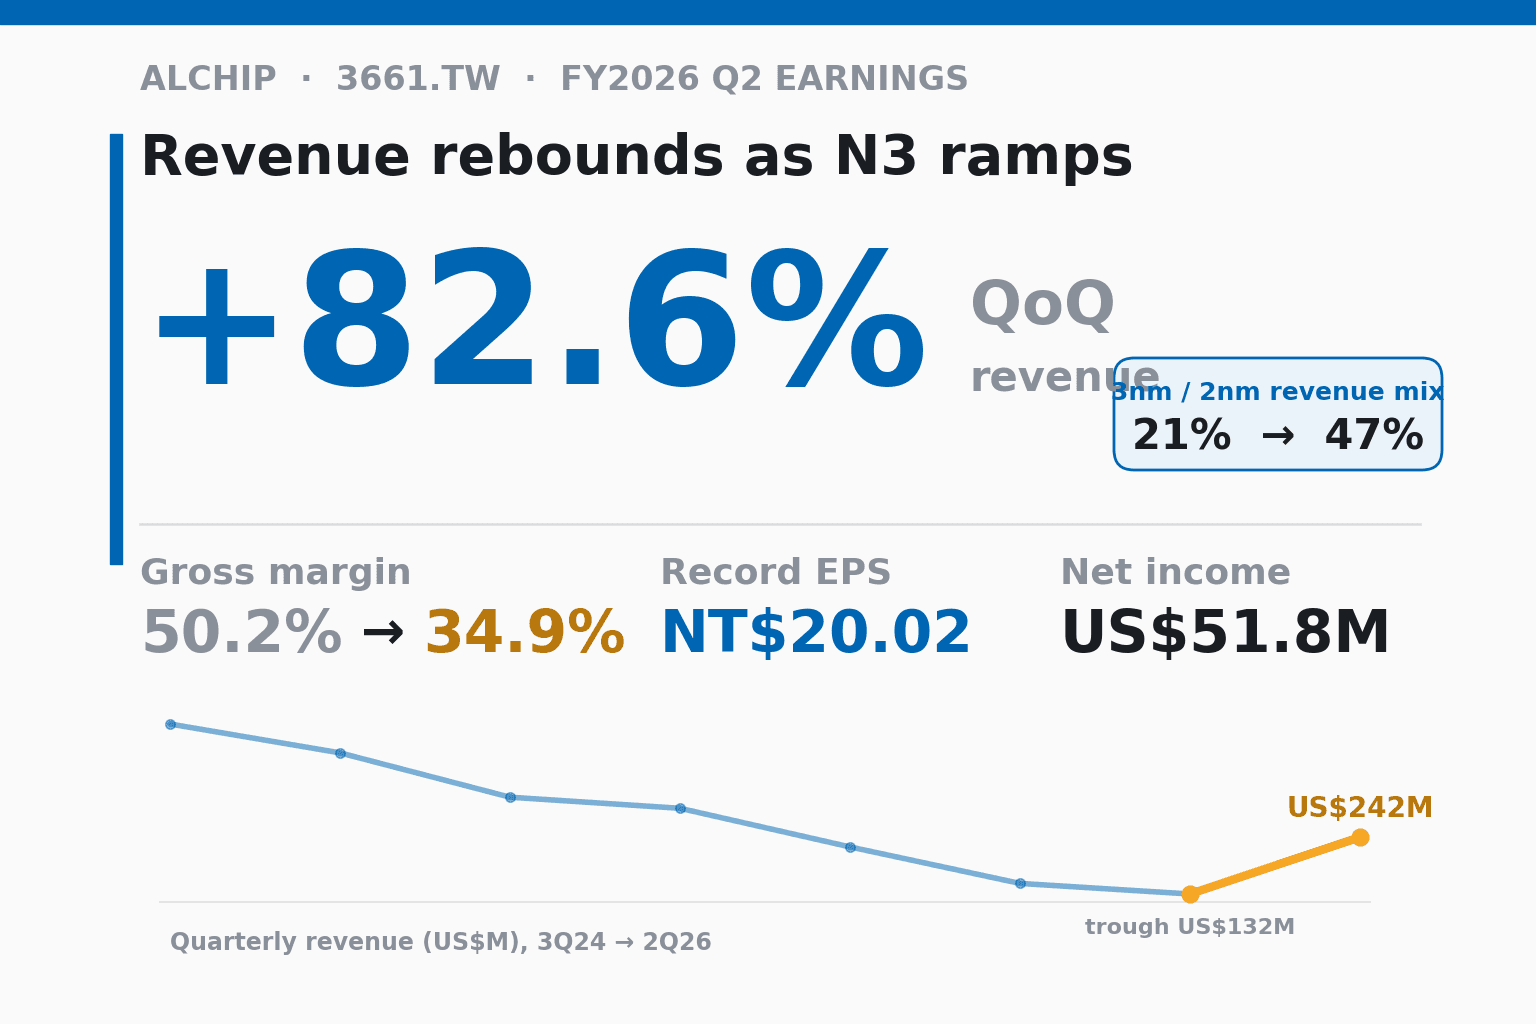
Alchip's Q2 2026 revenue came in at US$241.7M, up 82.6% from the prior quarter. Set against the past year of decline, the bounce alone is the story: the prior quarter's US$132.4M was a cyclical trough after five straight quarters of falling sales, and this quarter nearly doubled it. The "second-half surge" management had promised for three quarters just clicked its first piece into place.
The real engine is the N3 AI accelerator Alchip builds for a North American hyperscaler, which moved into volume production in late May. N3 here refers to TSMC's 3-nanometer process, and the market widely understands this accelerator to be Amazon's Trainium-3. The moment it started shipping, every structural line in the report shifted with it.
Yet the same report hides a seemingly contradictory reading: revenue doubled, but gross margin fell from the prior quarter's record 50.2% to 34.9%, while net income and EPS both set records. All three being true at once is the through-line of the quarter.
The full picture: revenue doubles, margin eases, profit peaks
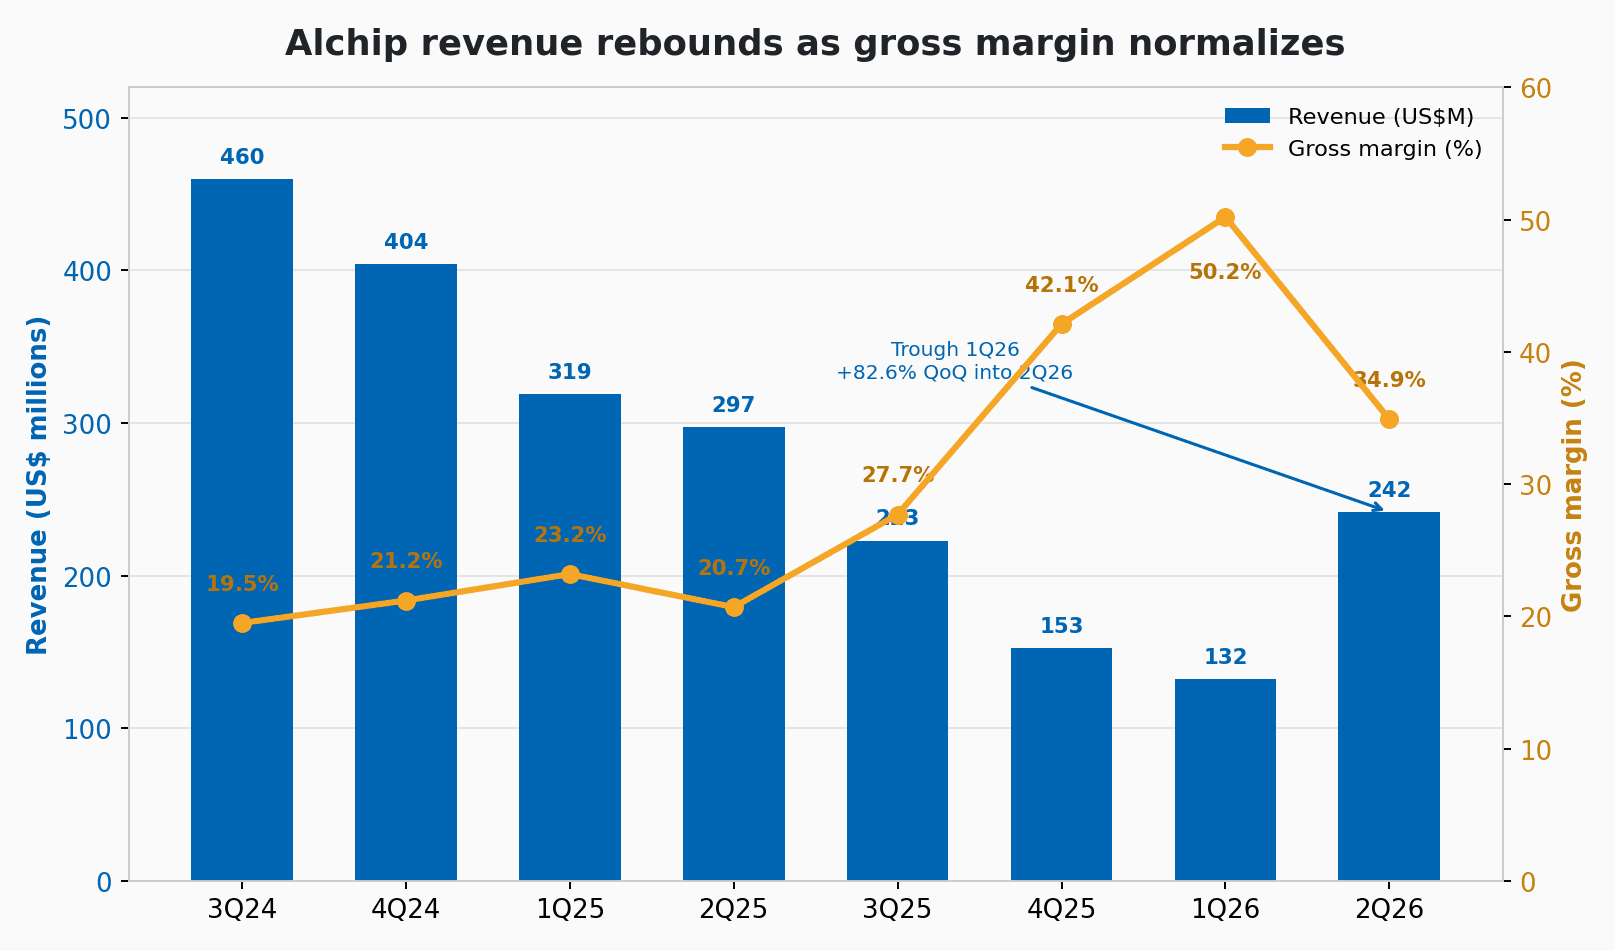
Laid out plainly: revenue of US$241.7M (up 82.6% QoQ, down 18.7% YoY); gross margin of 34.9%, down about 1,533 basis points QoQ, but still up 1,412 basis points YoY off a low year-ago base; operating margin of 21.6%, up 893 basis points YoY, showing the operating leverage the ramp brings. Net income of US$51.8M (up 14.9% QoQ, 20.7% YoY), and EPS of NT$20.02, a record for a single quarter, taking first-half cumulative EPS to NT$37.57.
One detail reveals the company's posture: operating expenses rose 38.6% QoQ to US$32.1M, driven by headcount and pay increases plus heavier use of EDA design tools and servers. This is spending laid down ahead of the ramp, not a one-off charge.
A note on convention: Alchip's functional currency is the US dollar, so revenue and profit are disclosed in dollars, with only EPS reported in New Taiwan dollars. The implied exchange rate this quarter is about NT$31.6 to US$1.
Process mix: 3nm/2nm vaults to 47%
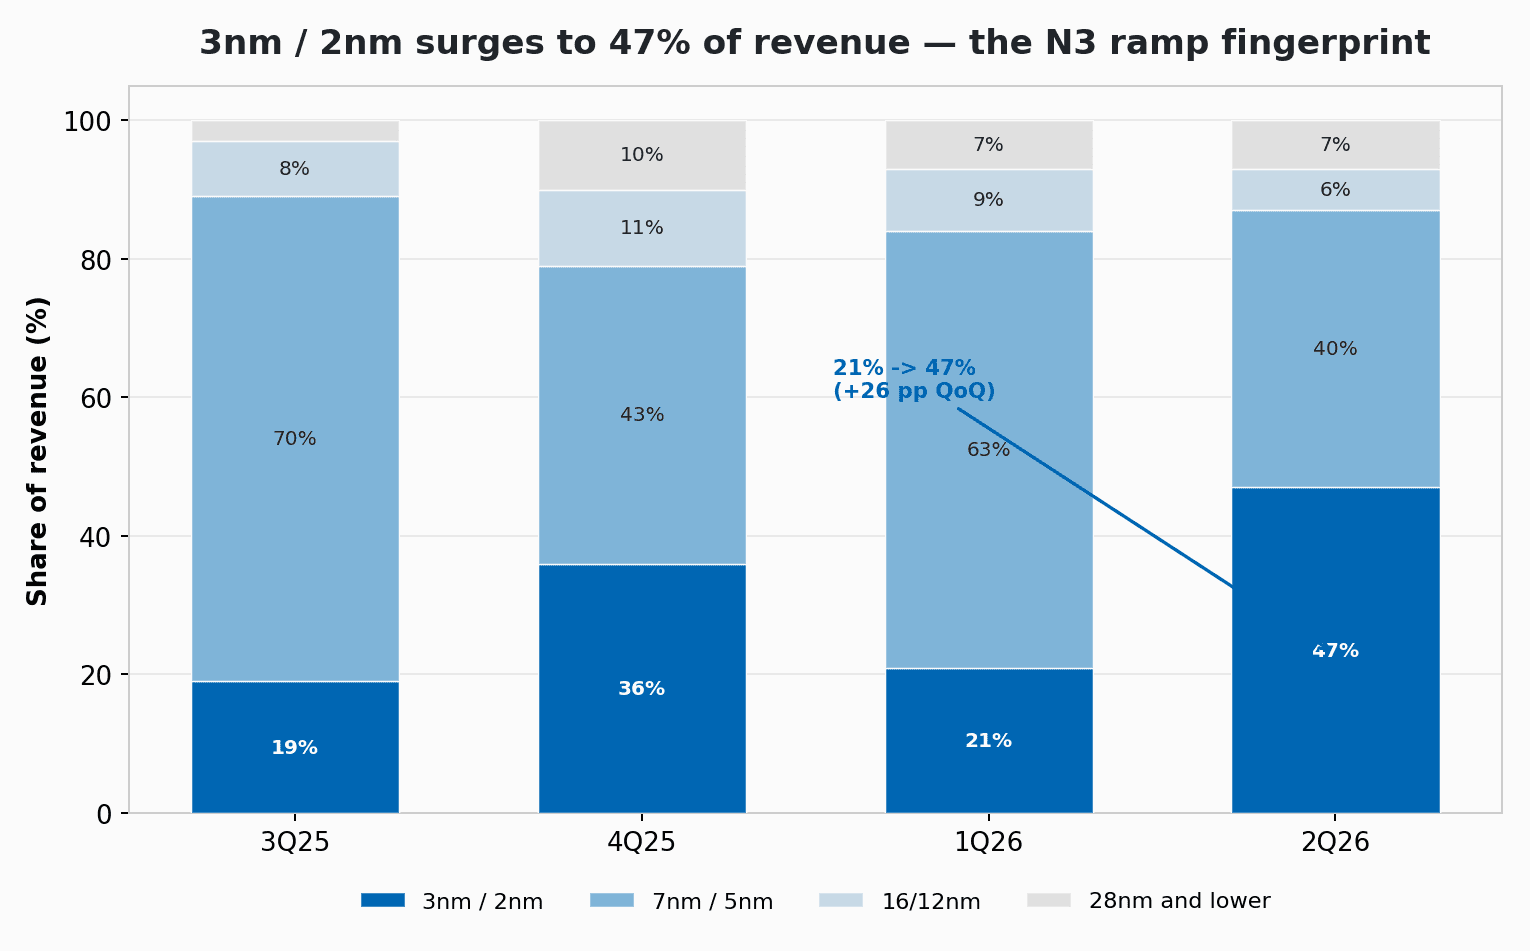
If you look at only one chart, make it this one. The 3nm/2nm share jumped from 21% last quarter to 47% of revenue this quarter, roughly US$114M, more than tripling QoQ. That is the direct fingerprint of the N3 accelerator ramp, and it also explains why gross margin was diluted: once leading-edge production revenue returns, the blended margin naturally drops. The tail of the prior 5-nanometer cycle (7nm/5nm) receded to 40% and keeps shrinking.
Put differently, the margin decline and this chart are two sides of one event. It is not weakening demand but a product mix switching from "almost pure design fees" back to the normal state of "design fees plus production."
Revenue and profit diverge again, only the direction flipped
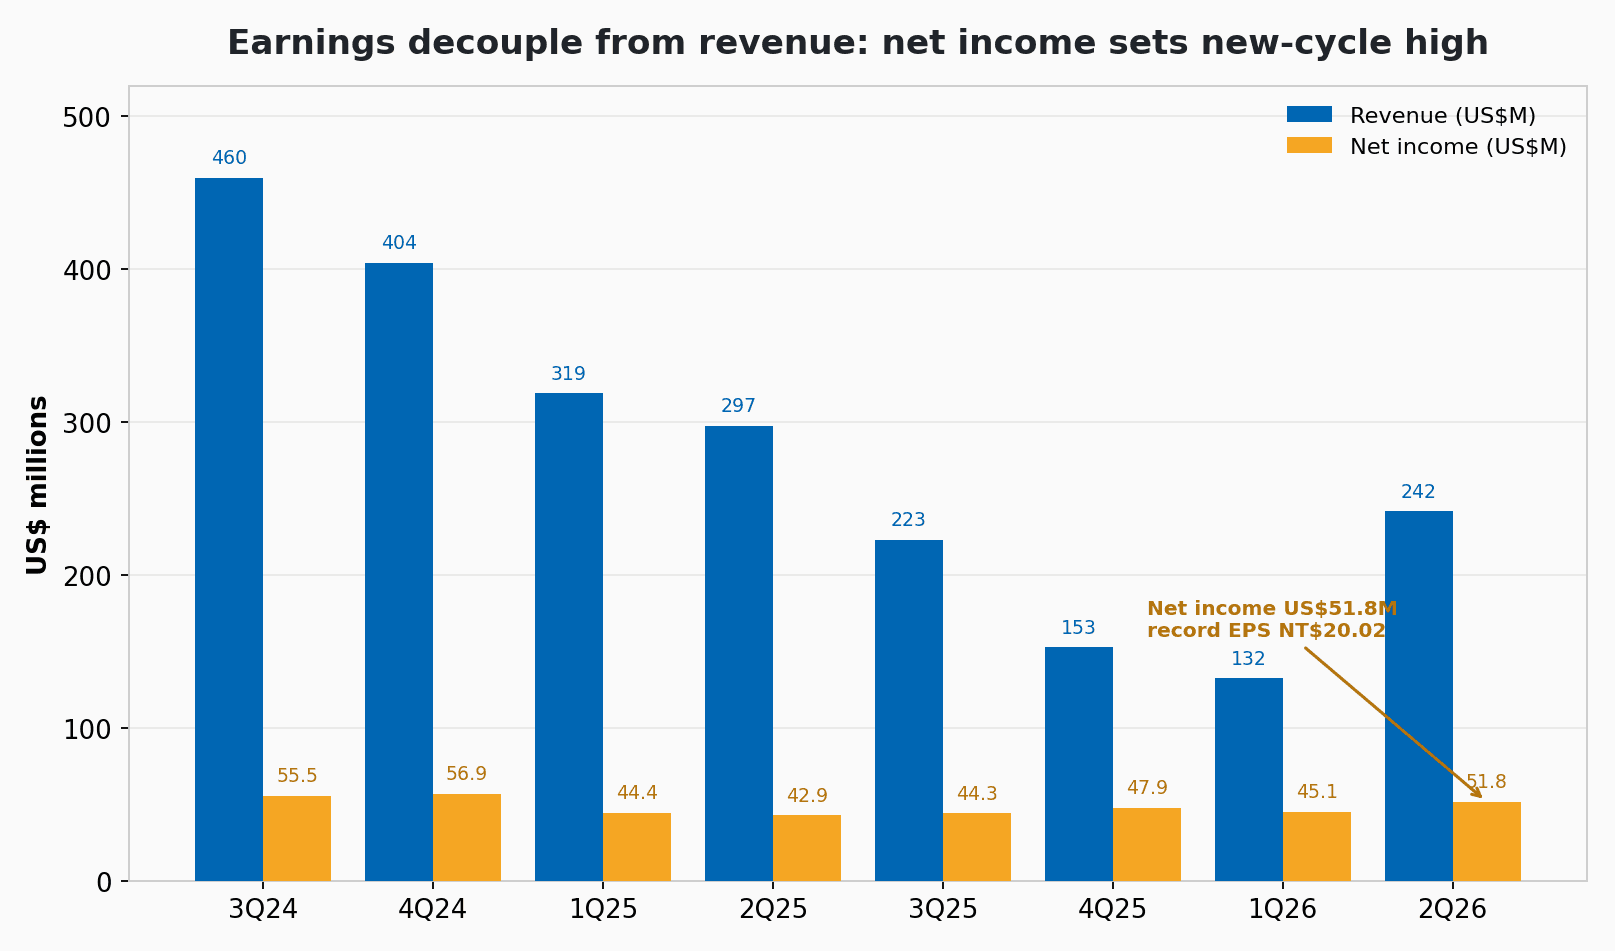
Last quarter's story was "revenue bottoms, profit holds," propped up by high-margin NRE. This quarter the direction flips: margin falls, profit hits a record, because the revenue that production brought in overwhelmed the margin drop.
Over the past eight quarters, revenue swung between US$132M and US$460M, a 3.5x spread from low to high, yet net income stayed pinned in a narrow US$43M to US$57M band. That relatively steady net-income line is the evidence that Alchip props up profit by alternating NRE and production. Management guides production gross margin toward about 20% from here, but as long as the ramp runs hard enough, the absolute profit dollars can still step up alongside it. That is the bull case for this stock right now: margin down, profit dollars up.
Geographic mix: North America back to 51% overnight
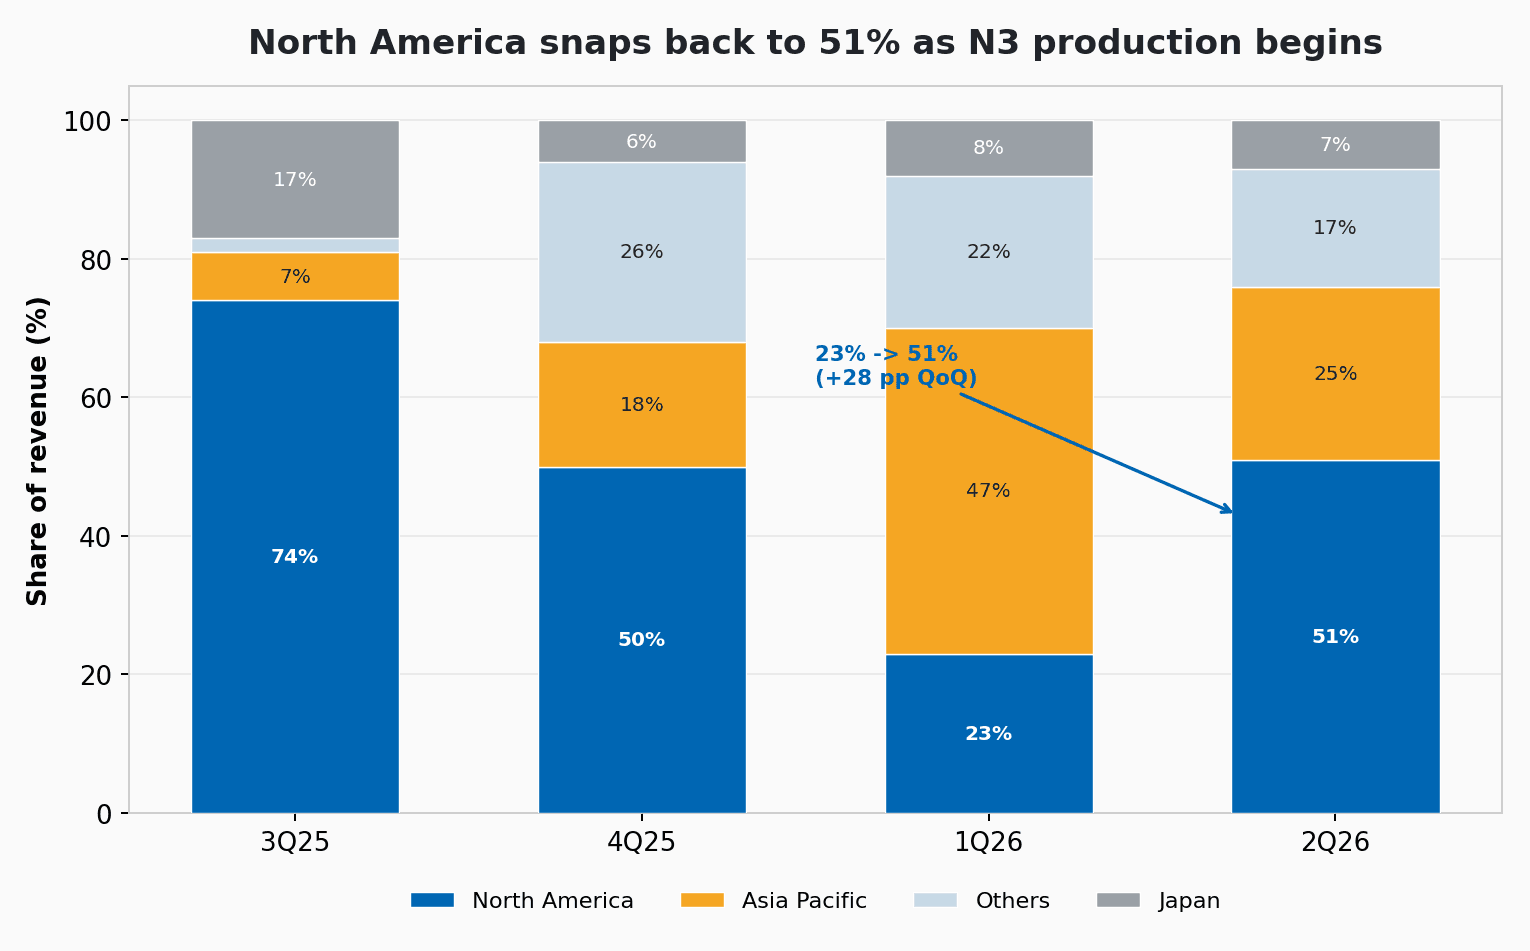
North America's share of revenue rebounded from 23% last quarter to 51%, about US$123M and up roughly 305% QoQ. The logic is simple: the N3 accelerator customer is a North American hyperscaler, so once production starts, North American revenue mechanically spikes. Asia-Pacific's surge to 47% last quarter was really the profile of a design- and NRE-heavy quarter; when US-side production returns, the geographic mix swings back toward North America.
What management said
The tone on the call was consistent from start to finish. Chairman Johnny Shen gave three clear statements: Q3 revenue and profit will both set records; Q4 will keep growing sequentially; and this growth is "not a matter of a single quarter or year," with existing production projects plus next-generation designs enough to underpin operating visibility across 2026 to 2029, a three-to-four-year window.
The full-year weighting of roughly 80/20 toward the second half already has one piece of hard evidence: July revenue of NT$7.433B, up 181.8% YoY, a record for any single month. Given that the N3 accelerator only shipped from late May with limited June contribution yet still drove full-quarter growth of 82.6% QoQ, a third quarter running the ramp at full tilt has a genuine shot at rewriting the record.
Looking ahead, two lines run at once. On the production side, the N3 accelerator keeps ramping through the whole third quarter, ADAS chips for Chinese automakers ship steadily, and next-generation projects near tape-out. On the design side, the 2-nanometer (N2) next-generation AI accelerator NRE project is expected to tape out (the milestone where a chip design is finalized and sent to the foundry) before year-end, with contract value, chip selling price, and design complexity all above the N3 generation. As for advanced packaging, management did not flag CoWoS (TSMC's advanced packaging technology) as a bottleneck for the 2026 ramp.
The analyst reaction: EPS peaks, but targets fall first
This was a two-sided print, and the analyst reaction was two-sided too. Sell-side sentiment before the report was extremely bullish, with UBS and BofA Securities both at NT$6,000 ahead of the call and the FactSet consensus median likewise at NT$6,000. After the print, analysts focused on the gross margin near 35% (below the prior quarter's 50%) and an N3 ramp pace short of the most optimistic models, and promptly cut 2026 full-year EPS from about 133.5 to roughly 115, resetting price targets from a consensus of about NT$6,000 toward NT$5,000.
But what was cut is the near-term number, not the long-term rating. Most brokers kept Buy and preserved the bullish 2027 scenario: 2027 revenue seen breaking NT$100B, with full-year EPS potentially around 165.
What this report really means
For the past three quarters, the bull-bear debate on this stock came down to one binary question: would the N3 ramp actually arrive? This quarter's answer is yes. Revenue up 82.6% QoQ, the 3nm/2nm share at 47%, and North America back to 51%: three structural lines confirming the same thing at once.
With the question answered, the battlefield shifts. What the market will argue about next is no longer "will the ramp arrive" but "where does production gross margin ultimately settle," and "how far can the N2 2027 pipeline re-rate the valuation." Margin will slide from 50% toward about 20%, but as long as revenue dollars grow fast enough, profit can be diluted on margin and set records on dollars at the same time.
The 2026 script has turned to its harvest chapter. The real suspense sits on the still-unwritten 2027 page: the N2 story.