Quanta Q2 2026: Revenue Tops NT$1tn, Record NT$7.43 EPS
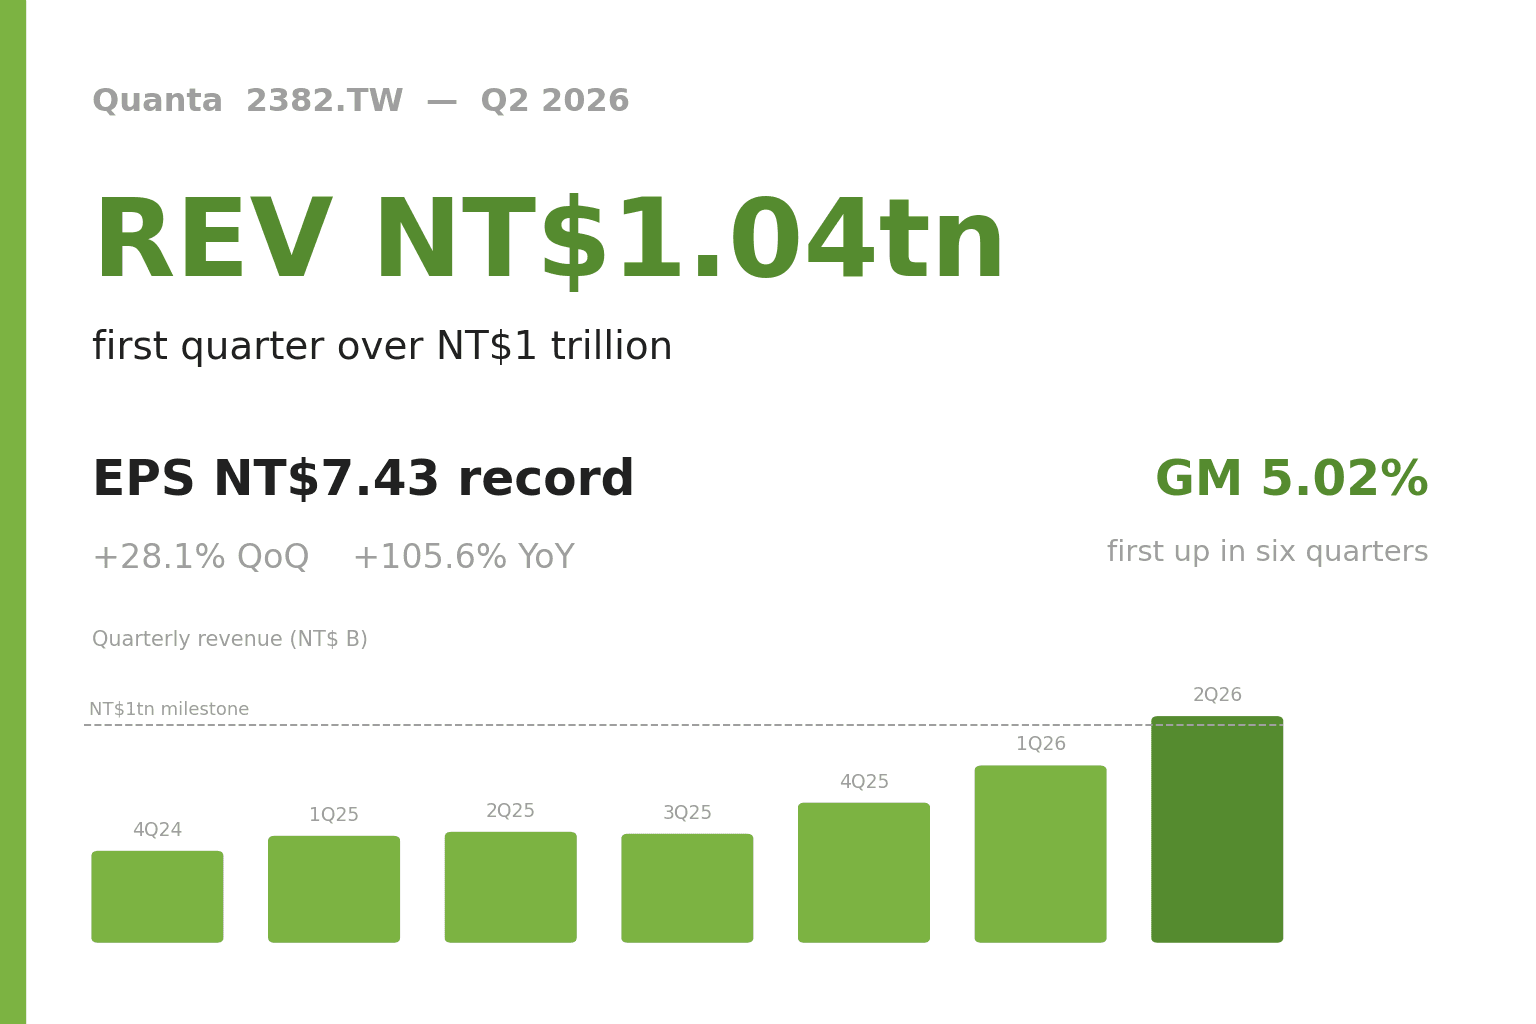
Taiwan's First Quarter Over NT$1 Trillion
Quanta Computer (2382.TW) crossed a psychological threshold in the second quarter of 2026: single-quarter revenue of NT$1.04 trillion (NT$1,036.6 billion to be exact), the first time any Taiwanese contract manufacturer has cleared NT$1 trillion in a single quarter. Revenue rose 28.1% QoQ and 105.6% YoY, a 2.06x jump in a single year.
But the number worth remembering is about more than fireworks on the top line. The company summed the quarter up as the "four highs": record revenue, gross profit, operating income, and earnings per share, all at the same time. EPS reached NT$7.43, Quanta's highest ever for a single quarter, up 35.1% QoQ and 70.0% YoY; net profit attributable to the parent was NT$28.65 billion, up 35.2% QoQ and 69.9% YoY.
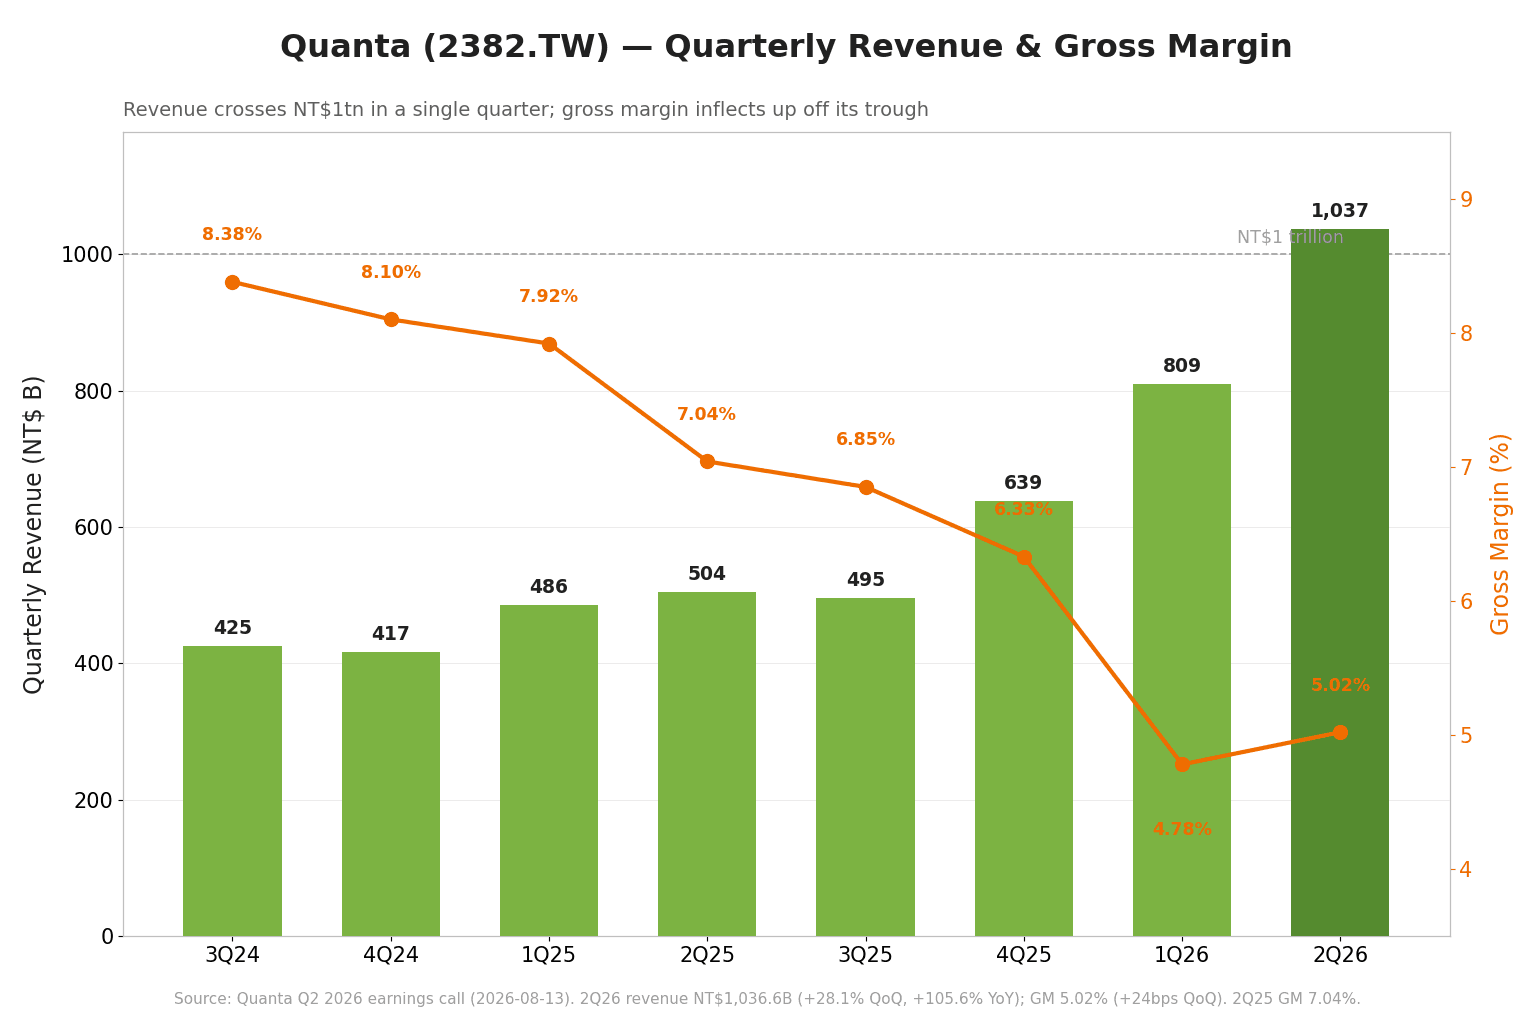
Looking back, this report is the payoff on a bet Quanta placed a quarter earlier. In the first quarter the company deliberately let gross margin sink to 4.78% (a 15-quarter low) to win AI-server volume; this quarter, the same volume plus higher rack prices carried profit all the way to a record.
The Real Turning Point: Gross Margin's First Rise in Six Quarters
If there is only one number to watch in this report, it is not the trillion-dollar revenue but gross margin of 5.02%.
Quanta's gross margin fell from above 8% in 2024 down through six straight quarters to 4.78% last quarter, and the market's biggest worry was whether "bigger AI, thinner margin" would harden into a structural problem the company could not walk back from. This quarter's 5.02%, up 0.24 percentage points QoQ, is the first time in six quarters the slide has stopped and reversed. Management's account: as the GB200-to-GB300 transition wrapped up, the margin dilution from high-end AI racks is "gradually converging," while one-off pilot-run and yield-learning costs faded.
Operating margin climbed in step, from 2.85% to 3.30% (up 0.46 points QoQ), with operating income of about NT$34.2 billion, up nearly 48% QoQ. That is because expenses rose only about 15%, far slower than the 35% growth in gross profit dollars, and operating leverage is clearly kicking in.
Still, keep the scale in view. At 5.02%, margin remains far below the 7.04% of a year earlier (down 2.02 points YoY), and the reason is the same expensive, heavy AI rack: the high-value GPU components booked into revenue mechanically inflate the denominator. So the right reading of this quarter is "the bottom is behind us and the direction is right," not "the margin is repaired."
AI Servers Are Now Quanta's Core, Near Two-Thirds of Revenue
The quarter's mix kept moving the same way: servers made up about 83% of revenue, and notebooks fell to roughly 13%.
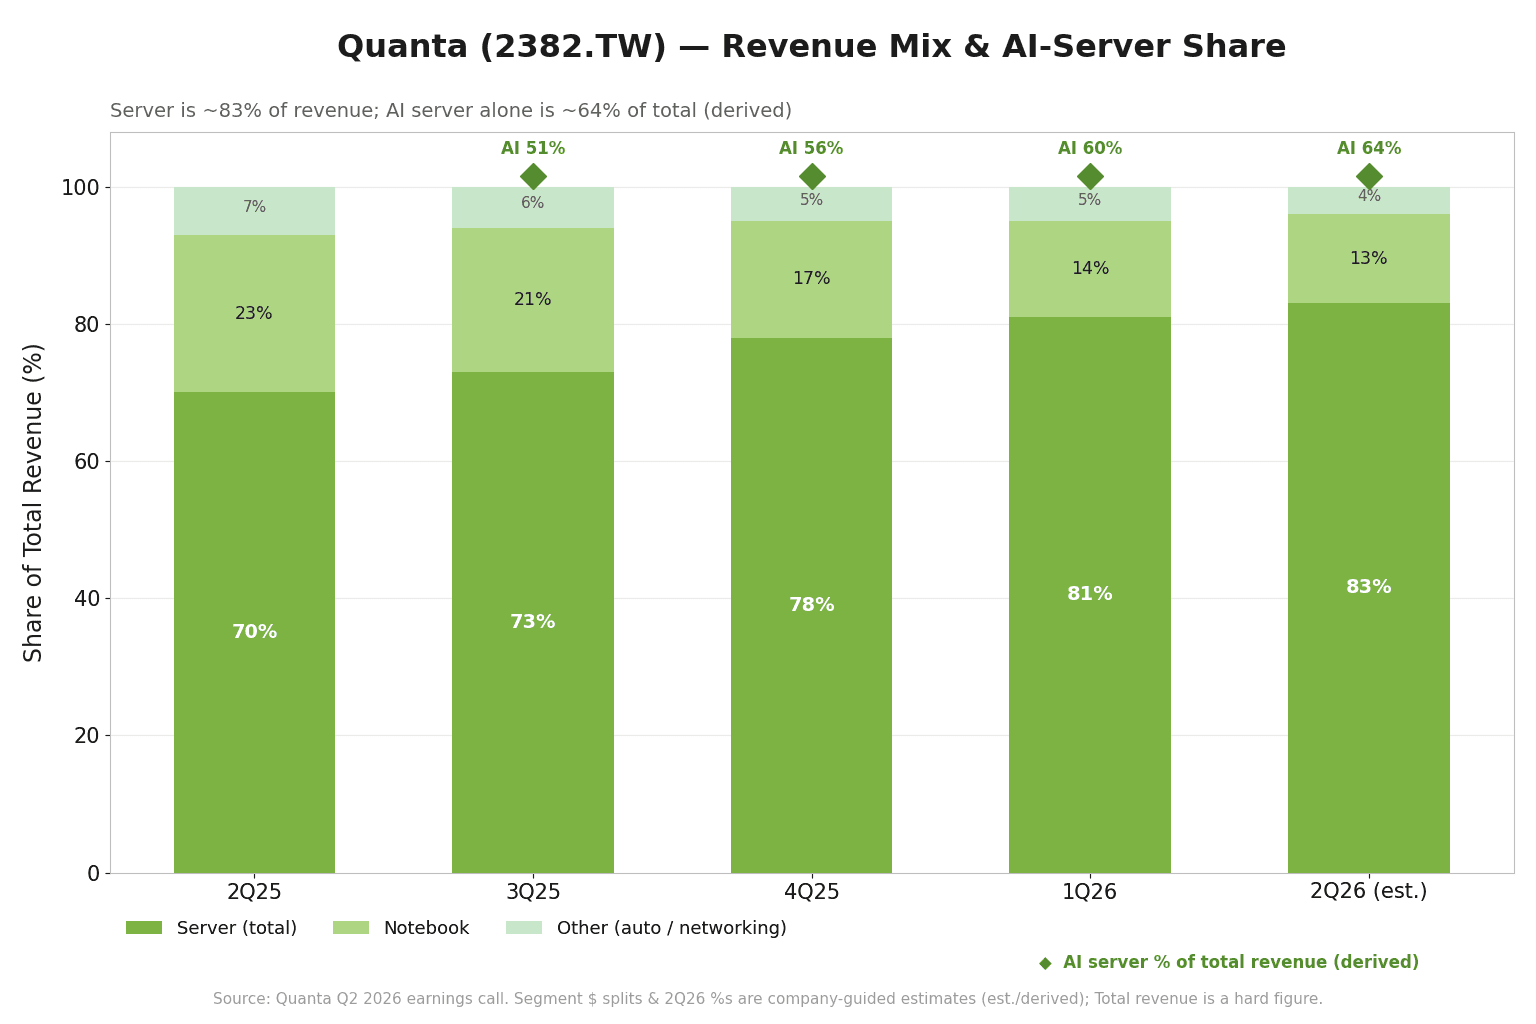
Within servers, AI servers made up 75%-80% of server revenue (the first-half range), and the company kept its full-year target of 80% and expects the share to keep rising in the second half. Applying those ratios back to the trillion-dollar top line, AI-server revenue for the quarter came to roughly NT$665 billion (an estimate with a wide error band), close to two-thirds of the total. That single business line would rank near the top of the entire Taiwan market on its own.
On platform generations, GB300 (NVIDIA's latest high-density rack; NVL72 refers to the highly integrated design of 72 GPUs per rack) was the quarter's shipping workhorse, with GB200 still shipping and customers wanting "both." Management called the platform transition "smooth," with only a one-to-two-month handoff gap between old and new and "no big hole." The next generation, Vera Rubin (VR200 NVL72), is nearing the end of test and validation; racks start shipping in Q3 and formally contribute revenue before year-end, so the baton pass is already scheduled.
The customer base is widening too. The top five cloud service providers (CSPs) remain the mainstay of AI-server revenue, but Quanta has begun shipping small volumes of GPU servers for NeoClouds (emerging GPU-cloud operators) and ASIC (customer-designed chip) servers for CSPs, and management says "the customer base will grow more diverse." ASICs are still under 10% of AI-server revenue, a line worth tracking from here.
EPS of NT$7.43: Half a Year Earns More Than a Share's Par Value
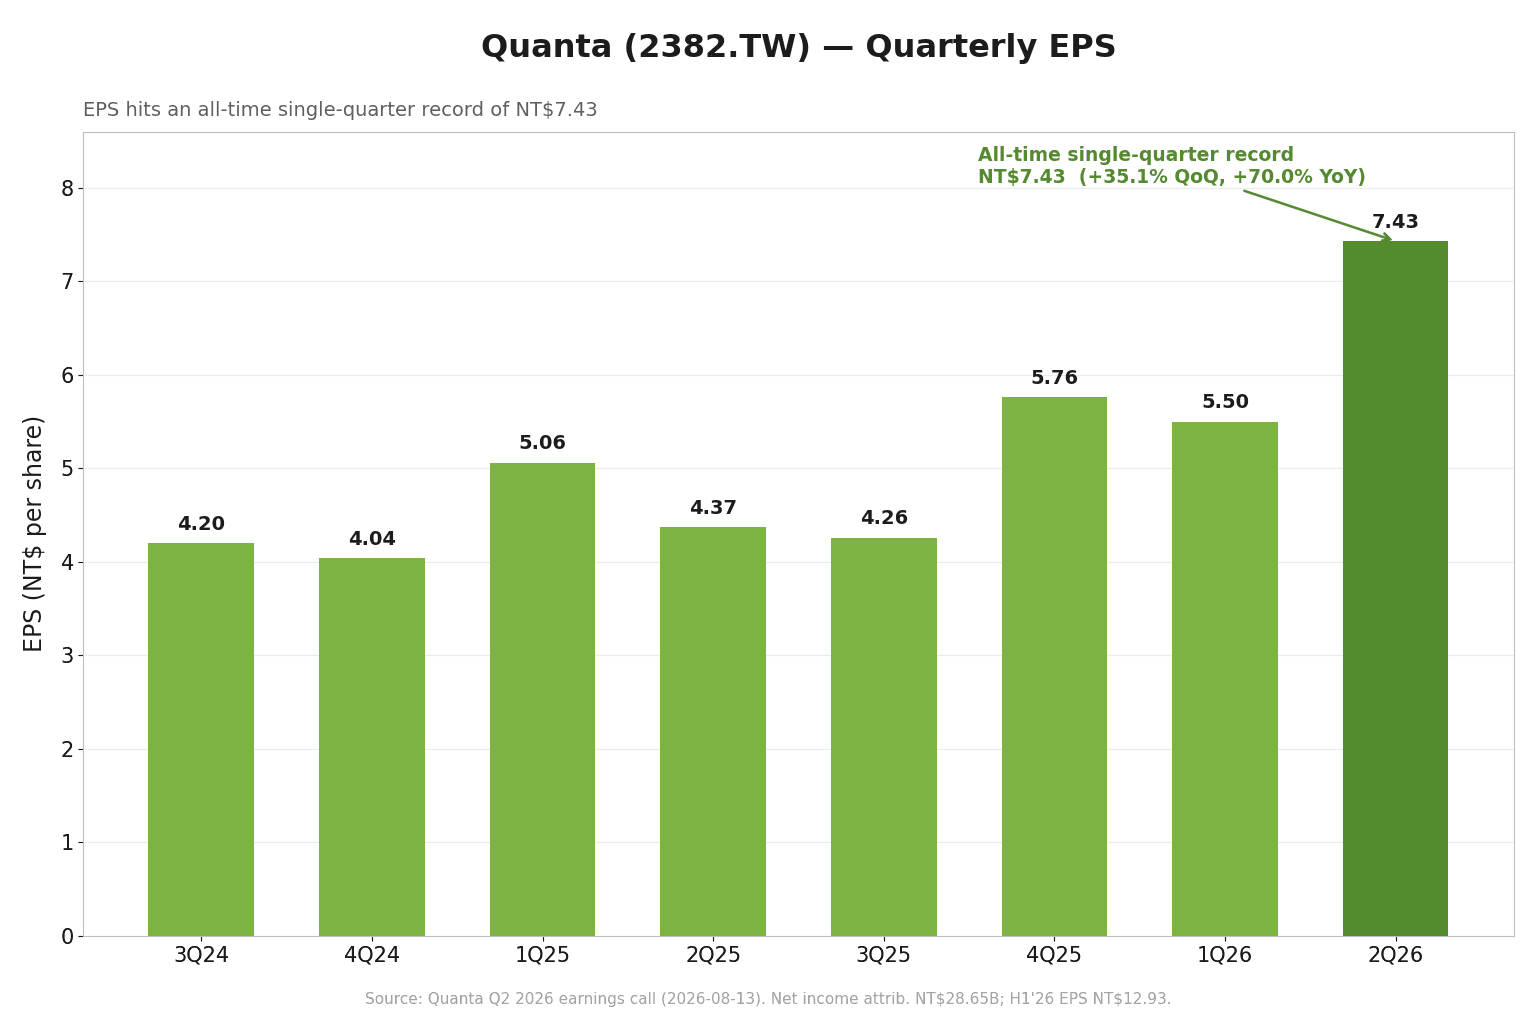
Put the two quarters together and first-half revenue was NT$1.85 trillion, up 86.5% YoY, with net profit attributable to the parent of NT$49.84 billion, up 37.1% YoY, and EPS of NT$12.93 — meaning Quanta earned more than a share's par value (NT$10) in just six months. Half a year of revenue has already eaten up 87% of last year's full-year NT$2.12 trillion.
Highlights of the Call: More Capex, Visibility to 2028, Consignment Begins
What really moved the market at this call (held after the close on 8/13, hosted by Morgan Stanley) was management's stance on the next two years.
Full-year capex was raised from NT$30 billion to NT$40 billion, a one-third increase in a single step and the most closely watched signal of the day. NT$21.8 billion was already spent in the first half, more than 80% of it at the California and Thailand plants. The accompanying move: in July the board approved buying AUO's Hwaya plant (Guishan, Taoyuan) for NT$19.7 billion, closing in Q4 2027 to support orders from 2028 onward and roughly doubling Taiwan's back-end AI assembly capacity; in August it injected US$973 million (about NT$31.8 billion) into its U.S. subsidiary to expand California capacity. The target of doubling AI-server capacity versus end-2025 by year-end is unchanged.
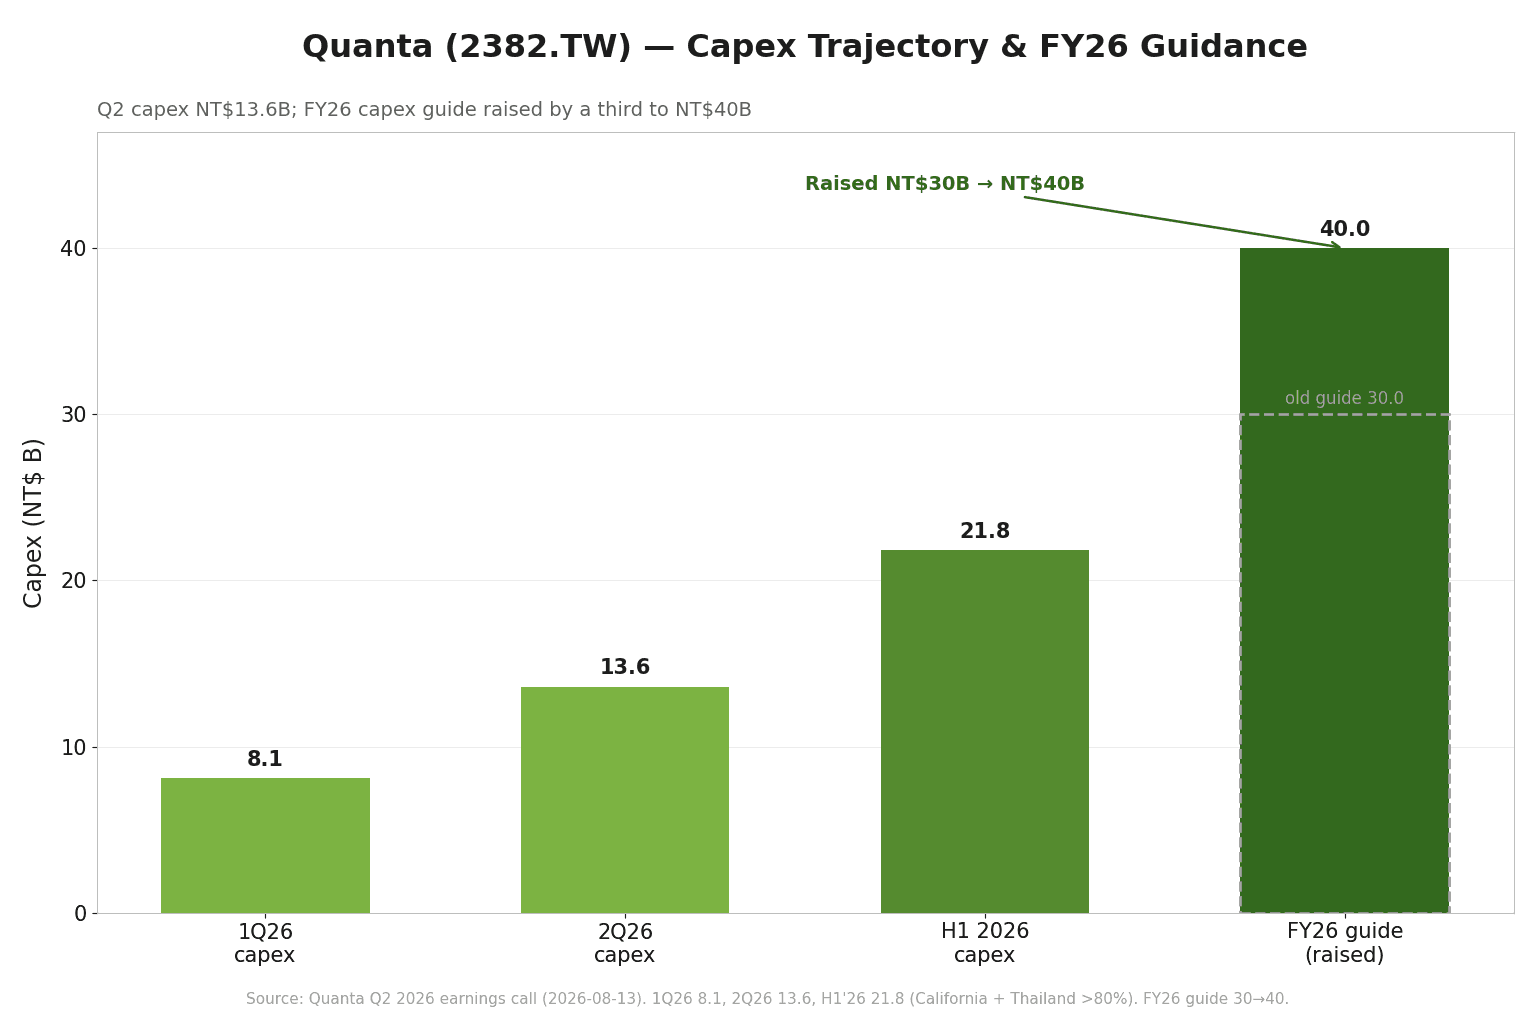
Management framed the capex hike as "a response to strong, predictable, visible customer demand," saying it sees none of the AI-demand cooling the market worries about. Order visibility now extends into 2028 (last quarter it was "beyond 2027"), customers are already discussing capacity and power planning for 2027-2028, and CFO Elton Yang said flatly that he is "very excited" about the next two years.
Another structural move is consignment: starting in Q3, high-value components (both GPUs and ASICs) on select AI-server projects shift from buy-and-sell to a model where the customer supplies the parts and Quanta only assembles and tests. That eases two things at once: the margin dilution from high-value parts, and the working-capital burden of fronting cash to buy GPUs. Customers are already signed up, but the share is still low for now, a benefit that pays off gradually.
As for notebooks, shipments rose 15% QoQ this quarter, better than expected, as customers rushed orders ahead of memory price hikes; but the second half turns cautious, with Q3 shipments cut by more than 20% in Quanta's own guidance and the full year seen down double digits, a "peak season that isn't peaking." This is one of the few soft spots in the report, and the line most sensitive to memory costs.
Market Reaction: Priced In, but Still Held
Analysts stay positive overall but keep a close eye on gross margin. Heading into the call, the consensus price target sat a bit above NT$390 (a FactSet median of about NT$394 across 22 analysts). Morgan Stanley kept an overweight rating with a target around NT$385 but preferred Wistron within the ODM group; Goldman Sachs named Wiwynn its top pick for "legacy-generation AI" and stayed relatively cautious on Quanta. Both point to the same thing: Quanta's margin structure gets marked down against its peers. Foxconn and Wistron, which reported the same day, both traded stronger than Quanta, extending the "Quanta lags" pattern that was already in place last quarter.
Reading the Quarter
If the first quarter was Quanta "trading margin for scale," the second quarter is where that bet starts paying back: scale kept expanding past the trillion mark, margin stopped falling and turned up, and EPS set a record. Those three things happening in one quarter are the finest part of this report.
The real questions are left for the second half. Whether consignment can keep margin climbing, whether Vera Rubin can take the baton from GB300 without a break, and whether the notebook cuts run deeper than expected: these three variables will decide whether Quanta can turn the "the bottom is in" story into a genuine "margin recovery" story. The gross-margin reading at the Q3 call in November will be the first checkpoint.