Hon Hai Q1 2026: Operating Profit Jumps 63% YoY, Cloud & Networking Hits 40% — Bigger Than iPhone for the First Time
A quarter where revenue grew 30% and operating profit grew 63%
Hon Hai's Q1 2026 revenue print is NT$2.13 trillion — up 29.68% YoY, down 19% QoQ (seasonal: post-iPhone launch, pre-next-cycle production lull). EPS NT$3.56, net income NT$49.92B (+19% YoY). All clean numbers. None of those is the most important number on the page.
The number that matters is operating profit NT$75.65B, up 63% YoY — far outpacing the +30% revenue growth. It's the largest single-quarter YoY operating profit step-up in eight quarters.
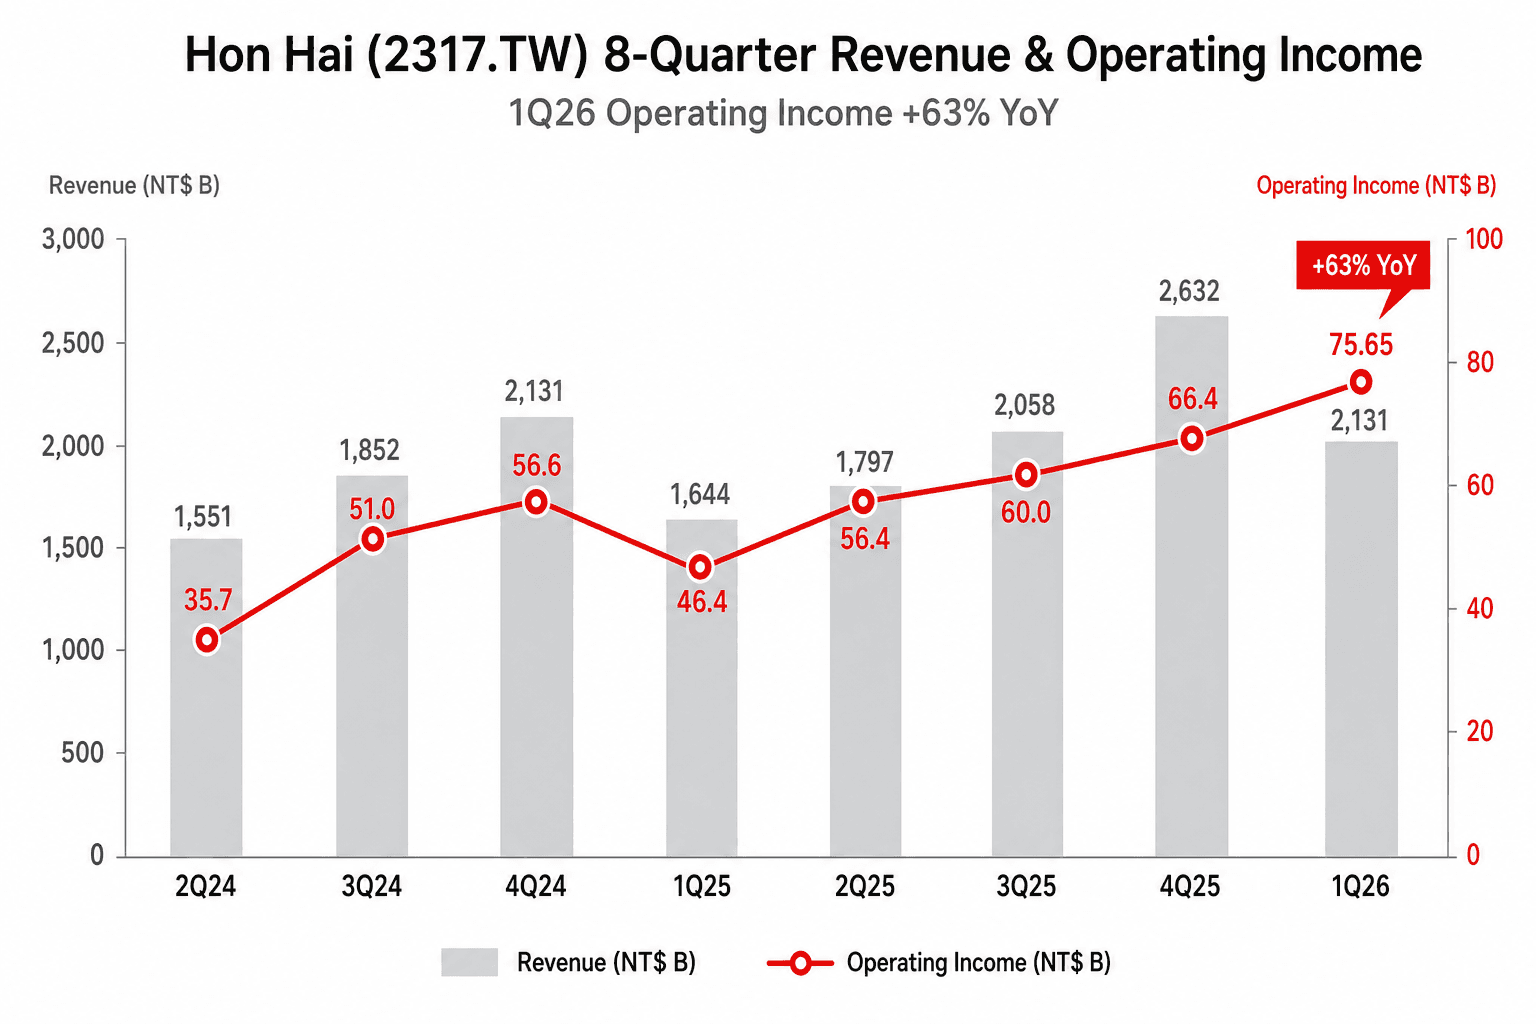
The "revenue +30%, OP +63%" scissor isn't accounting magic. It's real operating leverage, with three layers underneath: (1) Cloud & Networking mix jumped sharply, AI rack invoices are large, line utilization is high, OpEx barely moves with each marginal unit — so a much larger share of incremental revenue lands in OP. (2) Gross margin recovered from 5.88% (4Q25) to 6.15%, as the Buy-and-Sell parts pass-through dilution from the AI server ramp got outpaced by scale leverage. (3) OpEx fell 37% QoQ as the seasonal year-end front-loading normalized.
But the real protagonist of this print is the next chart.
Cloud & Networking 40% — bigger than iPhone for the first time
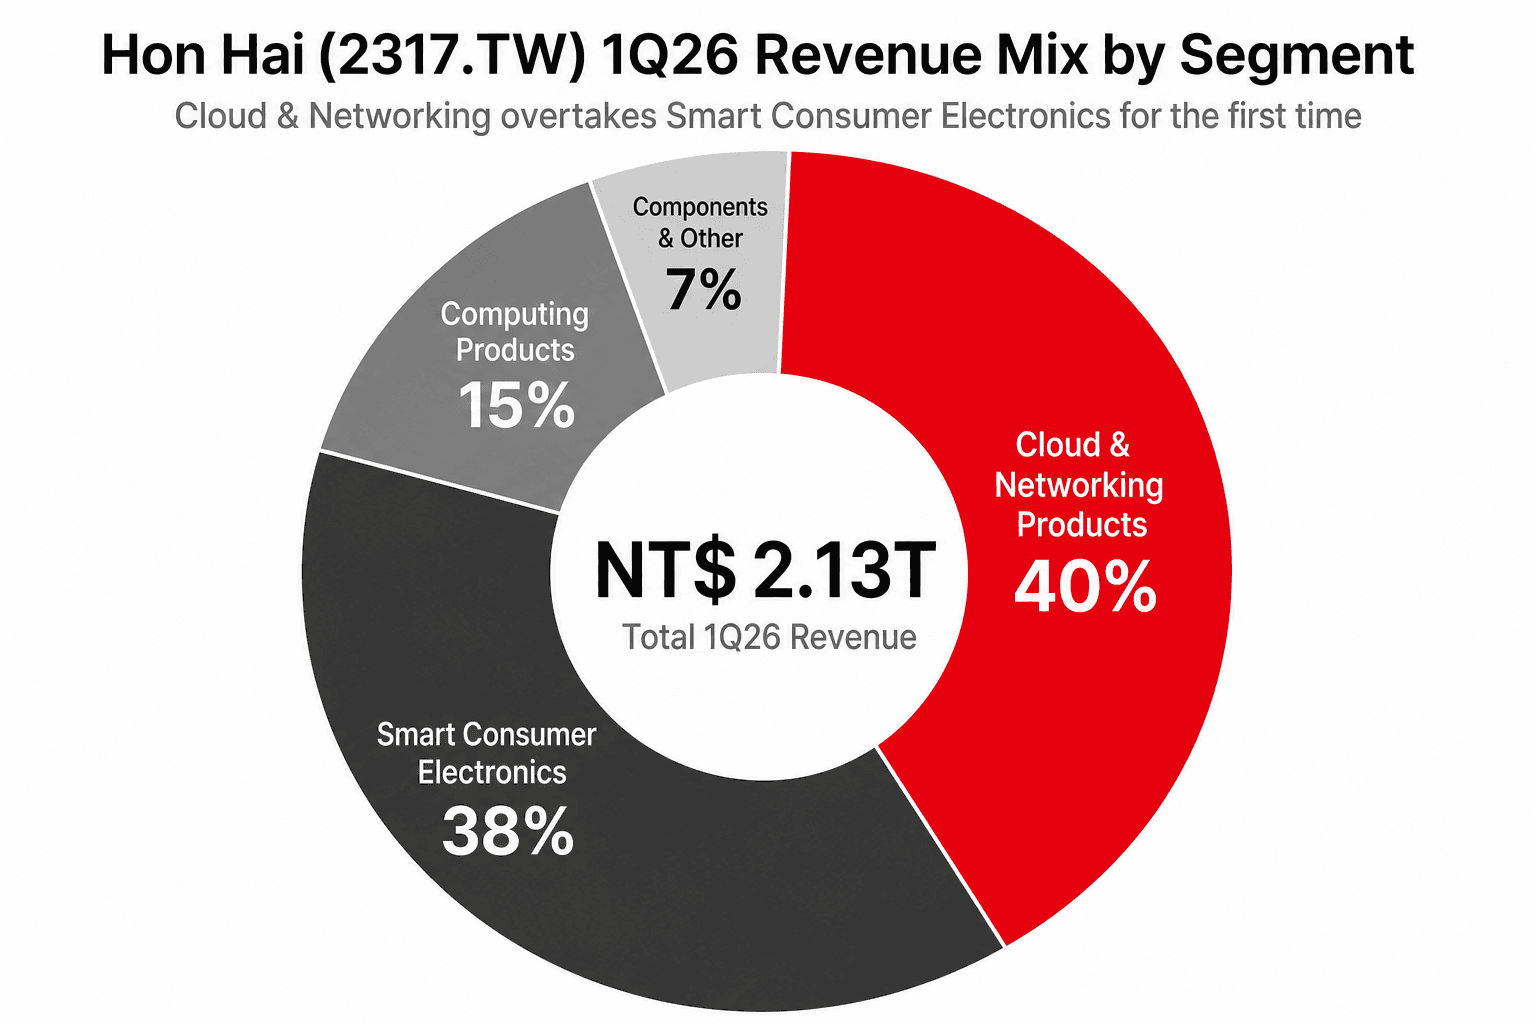
This chart is the heart of Hon Hai's 2026 story. A year ago in 1Q25, Cloud & Networking was 25% of revenue and Smart Consumer Electronics (including iPhone) was 49% — Hon Hai was an iPhone contractor that also did some servers. One year later in 1Q26, the two segments officially crossed:
- Cloud & Networking Products: 40% (NT$852B, +107% YoY)
- Smart Consumer Electronics: 38% (NT$810B, +0.6% YoY)
- Computing Products: 15% (NT$320B, -7.4% YoY)
- Components & Other: 7% (NT$149B, +81.5% YoY)
That single segment grew 107% YoY. Meaning: AI server-driven Cloud & Networking revenue more than doubled YoY. iPhone (inside Smart Consumer) was essentially flat. So nearly every additional dollar Hon Hai earned in Q1 2026 came from AI server and Cloud & Networking.
The multi-year trajectory of Cloud & Networking share
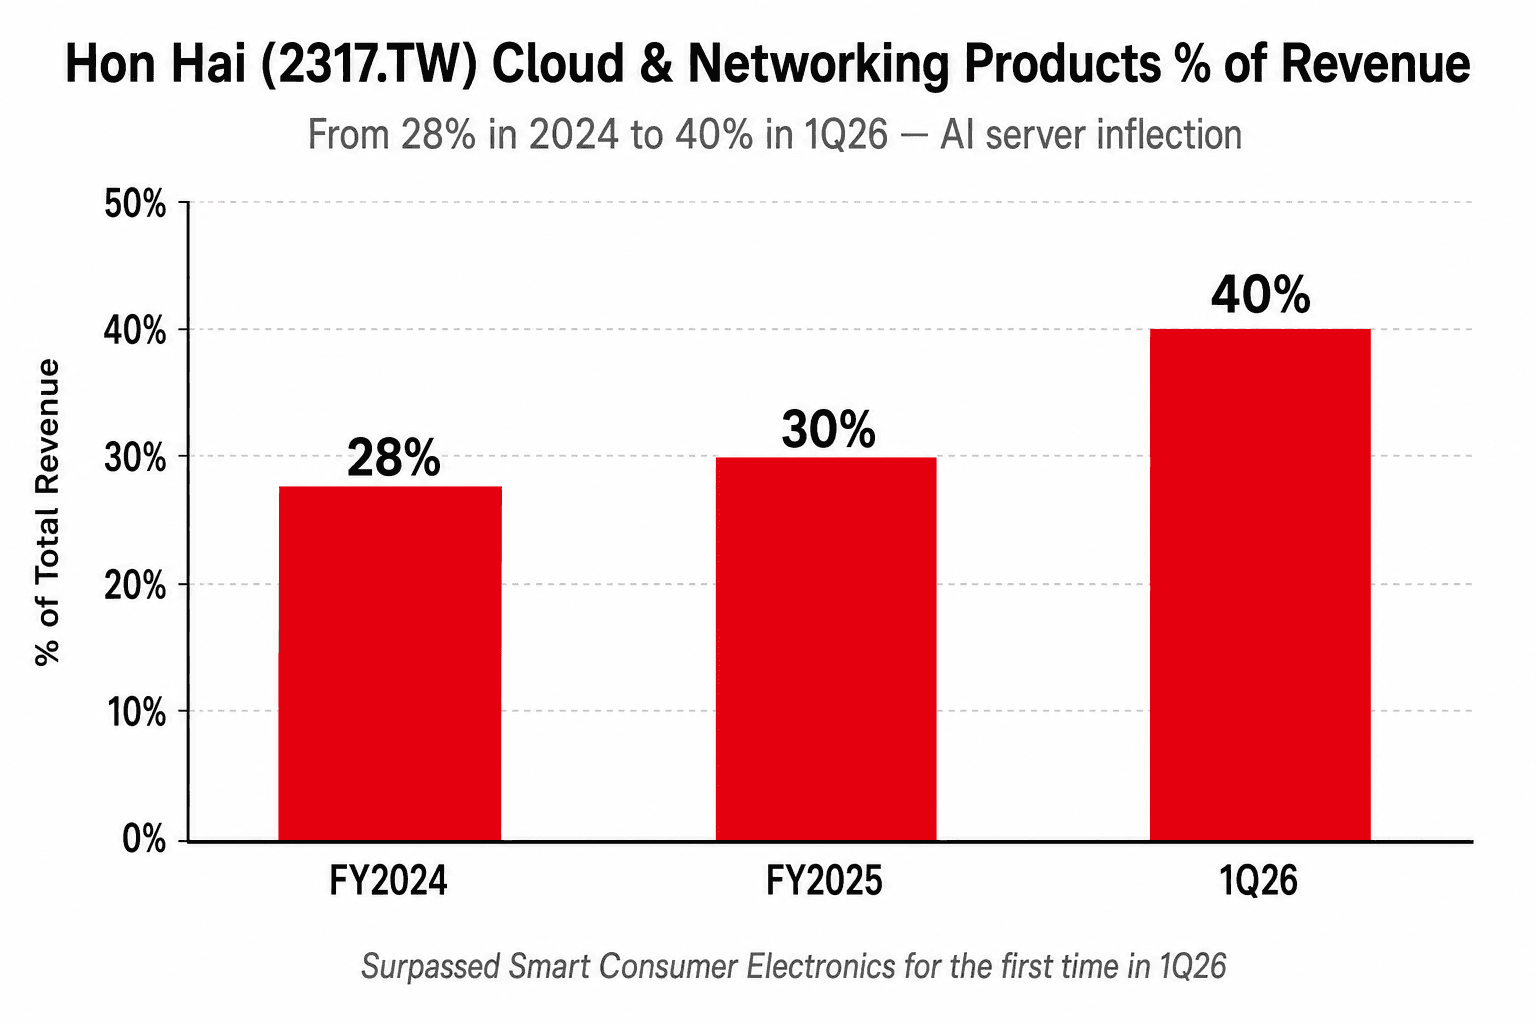
Plot Cloud & Networking share over multiple years and the inflection is unmistakable:
- FY2024: 28%
- FY2025: 30%
- 1Q26: 40%
Two years of slow ramp added 2 percentage points. This single quarter added 10 points. That's not linear penetration — that's an inflection.
What's driving the inflection is two numbers Liu Young-Way put on the slides directly: 2026 AI rack shipments to grow "by a multiple" (i.e. 100%+ versus the 2025 base of ~30K units, into the 60K-75K range), and Hon Hai's global AI server market share at ~40% in 2026 climbing to ~50% in 2027. That latter number is grounded in industry estimates of Nvidia rack shipments at 75K in 2026 and 100-110K in 2027 — Hon Hai is claiming half the cake.
The "6%+" structural margin target finally returns
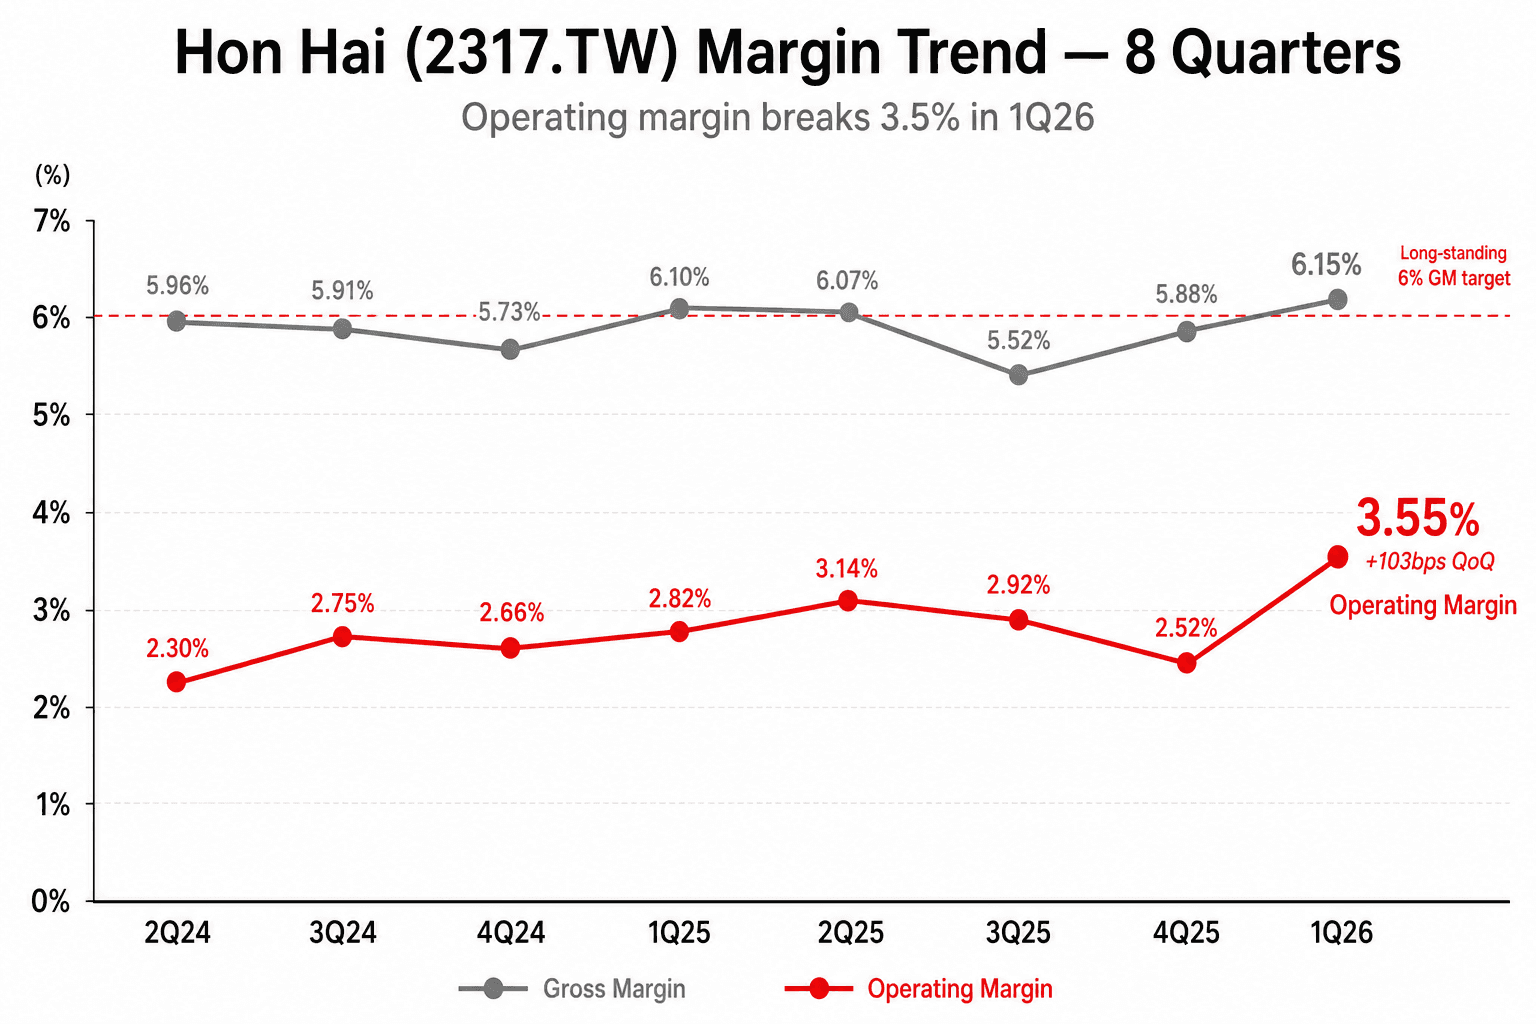
Hon Hai's gross margin has had a "6%+" structural target for over a decade. At every earnings call management gets asked some version of "when do you get above 6% sustainably?" The last three quarters have been pressured by the Buy-and-Sell business model on AI servers — where customer-supplied GPUs and HBM get booked through the P&L at near-cost margin. That dropped GM to 5.52% in 3Q25 and 5.88% in 4Q25.
Q1 2026 GM printed 6.15% — back above the 6% structural target. The CFO's commentary was carefully hedged: "We are not raising the structural target." But the mathematical reality is that as AI server revenue mix moves from 25% to 40% and absolute volume keeps scaling, scale leverage outrunning Buy-and-Sell dilution is just a matter of time. Q2's GM read is the deciding data point on whether 6.15% is the new floor or a one-quarter mix benefit.
The bigger surprise is operating margin at 3.55% — an eight-quarter high, up 103 bps QoQ from 4Q25's 2.52%. The 76 bp gap between GM expansion (+27 bps) and OPM expansion (+103 bps) is the operating leverage made visible.
iPhone: India capacity holds Smart Consumer flat
Smart Consumer Electronics revenue NT$810B, +0.6% YoY — looks unremarkable, actually evidence of execution.
Over the last 18 months Hon Hai has executed a brutal supply-chain transition: most US-bound iPhones now come from India, not China. Liu confirmed in Q&A: "Most of the iPhones we ship to the US now come from India." That a segment going through that kind of geographic shift held revenue and margin essentially flat means Indian line yields and cost structure have hit ~90%+ of the China benchmark.
Why this matters for the bull case: the AI server explosion is incremental, not cannibalistic. Hon Hai isn't trading iPhone share for AI server share. It's adding AI server on top of an iPhone business that itself is stable.
The moat is in Mexico and Texas
The most important sentence Liu said wasn't a financial number, it was: "The world's largest AI server factory will be in Texas." That sentence sits on top of two facts:
- Mexico Guadalajara plant — at full ramp, with assembly floor space tripled in 2H25 and a FY26 AI rack capacity target of 30K units. The current workhorse.
- Texas Houston plant — under construction, first racks in Q4 2026. The future flagship, positioned as "the world's largest AI server factory." Customer base: US CSPs and sovereign AI projects — clients who need US-soil manufacturing for policy, security clearance, or ITAR-adjacent reasons that don't move with tariff rates alone.
Quanta (2382), Wiwynn (6669), and Wistron (3231) all have similar North American capacity plans on paper. None has Hon Hai's 12-18 month lead in actually breaking ground and ramping. In a 2026-2027 AI rack demand window, that lead time is the moat.
The rerating has partially happened
On the multiples math:
- Hon Hai's historical forward P/E has been 12-14× (typical contract manufacturer multiple)
- AI infrastructure suppliers (Vertiv, Eaton, etc.) trade at 22-30× forward P/E
- Sell-side consensus after this print is moving the median forward P/E from 13× to 17-18×
- FY26 EPS estimates are moving from NT$14.8 to NT$15.6 (consensus median), implying NT$265 at 17× and NT$281 at 18×
The 5/15 close at NT$305.5 is already above the upper end of that new consensus range — meaning the market has partially priced the rerating, but the gap from old to new isn't fully walked. Sell-side median PT moved from NT$285 to ~NT$320; the most bullish names (Morgan Stanley, Macquarie, Yuanta) all sit at NT$340.
| Broker | Rating | New PT |
|---|---|---|
| Morgan Stanley | Overweight | NT$340 |
| Macquarie | Outperform | NT$340 |
| Yuanta | Buy | NT$330 |
| Goldman Sachs | Buy (Conviction) | NT$330 |
| Citi | Buy | NT$325 |
| JPMorgan | Overweight | NT$320 |
Reading the print
Hon Hai 1Q26 has a one-line story: this is the official confirmation point for Hon Hai's transition from iPhone contract assembler to core AI infrastructure supplier.
- Cloud & Networking 40% > Smart Consumer 38% — structural inflection
- Operating profit +63% YoY, OPM 3.55% (8-quarter high) — operating leverage delivered
- Gross margin back to 6.15% above structural target — Buy-and-Sell dilution starting to lose
- "Multiple-fold AI rack growth" + "50% global share by 2027" — management's clearest forward 18-month frame
- Houston + Guadalajara dual base — a moat competing ODMs can't replicate quickly
What's left is execution. May and June monthly revenue (out by ~6/10 and ~7/10) is the first validation point. May print above the prior-year NT$640B and June acceleration on top would lock in the "multiple-fold" guide and trigger another wave of EPS and PT raises. If monthly cadence disappoints, 1Q26 starts getting reframed as a one-quarter surprise rather than a structural turn.
Either way, this print has irreversibly put Hon Hai inside the "core AI infrastructure" conversation. For a NT$4-trillion-market-cap name, that conversation alone is the start of the rerating.